Coffee prices ease as supply outlook improves
- Arabica and Robusta futures prices have fallen in recent days, amid growing expectations of a shift in the global supply outlook.
- While Brazilian export figures are expected to show a strong recovery in August, rainfall has reached the country's coffee-producing regions, with more precipitation expected in the coming weeks, favoring the development of the 27/28 season.
- On the Robusta side, partial export data from Vietnam also shows that the country’s exports continue on the upside, increasing the prospects of ample supply in the short term. At the same time, Robusta certified stocks have also recovered in the past weeks.
- On the macroeconomic side, the recent hike in the U.S. and other major economies' treasury bonds could also contribute to the current volatility in the market.
Coffee prices ease as supply outlook improves
If flowering is substantial, it would likely add further pressure on prices. Technical momentum in the Arabica market also remains neutral, with the Relative Strength Index (RSI) not yet in oversold territory, leaving room for additional downside in the December/26 contract. Should weather conditions in Brazil remain favorable, Arabica prices are likely to remain below 300 c/lb.
Cumulative Precipitation in Brazil’s Coffee Regions (mm)
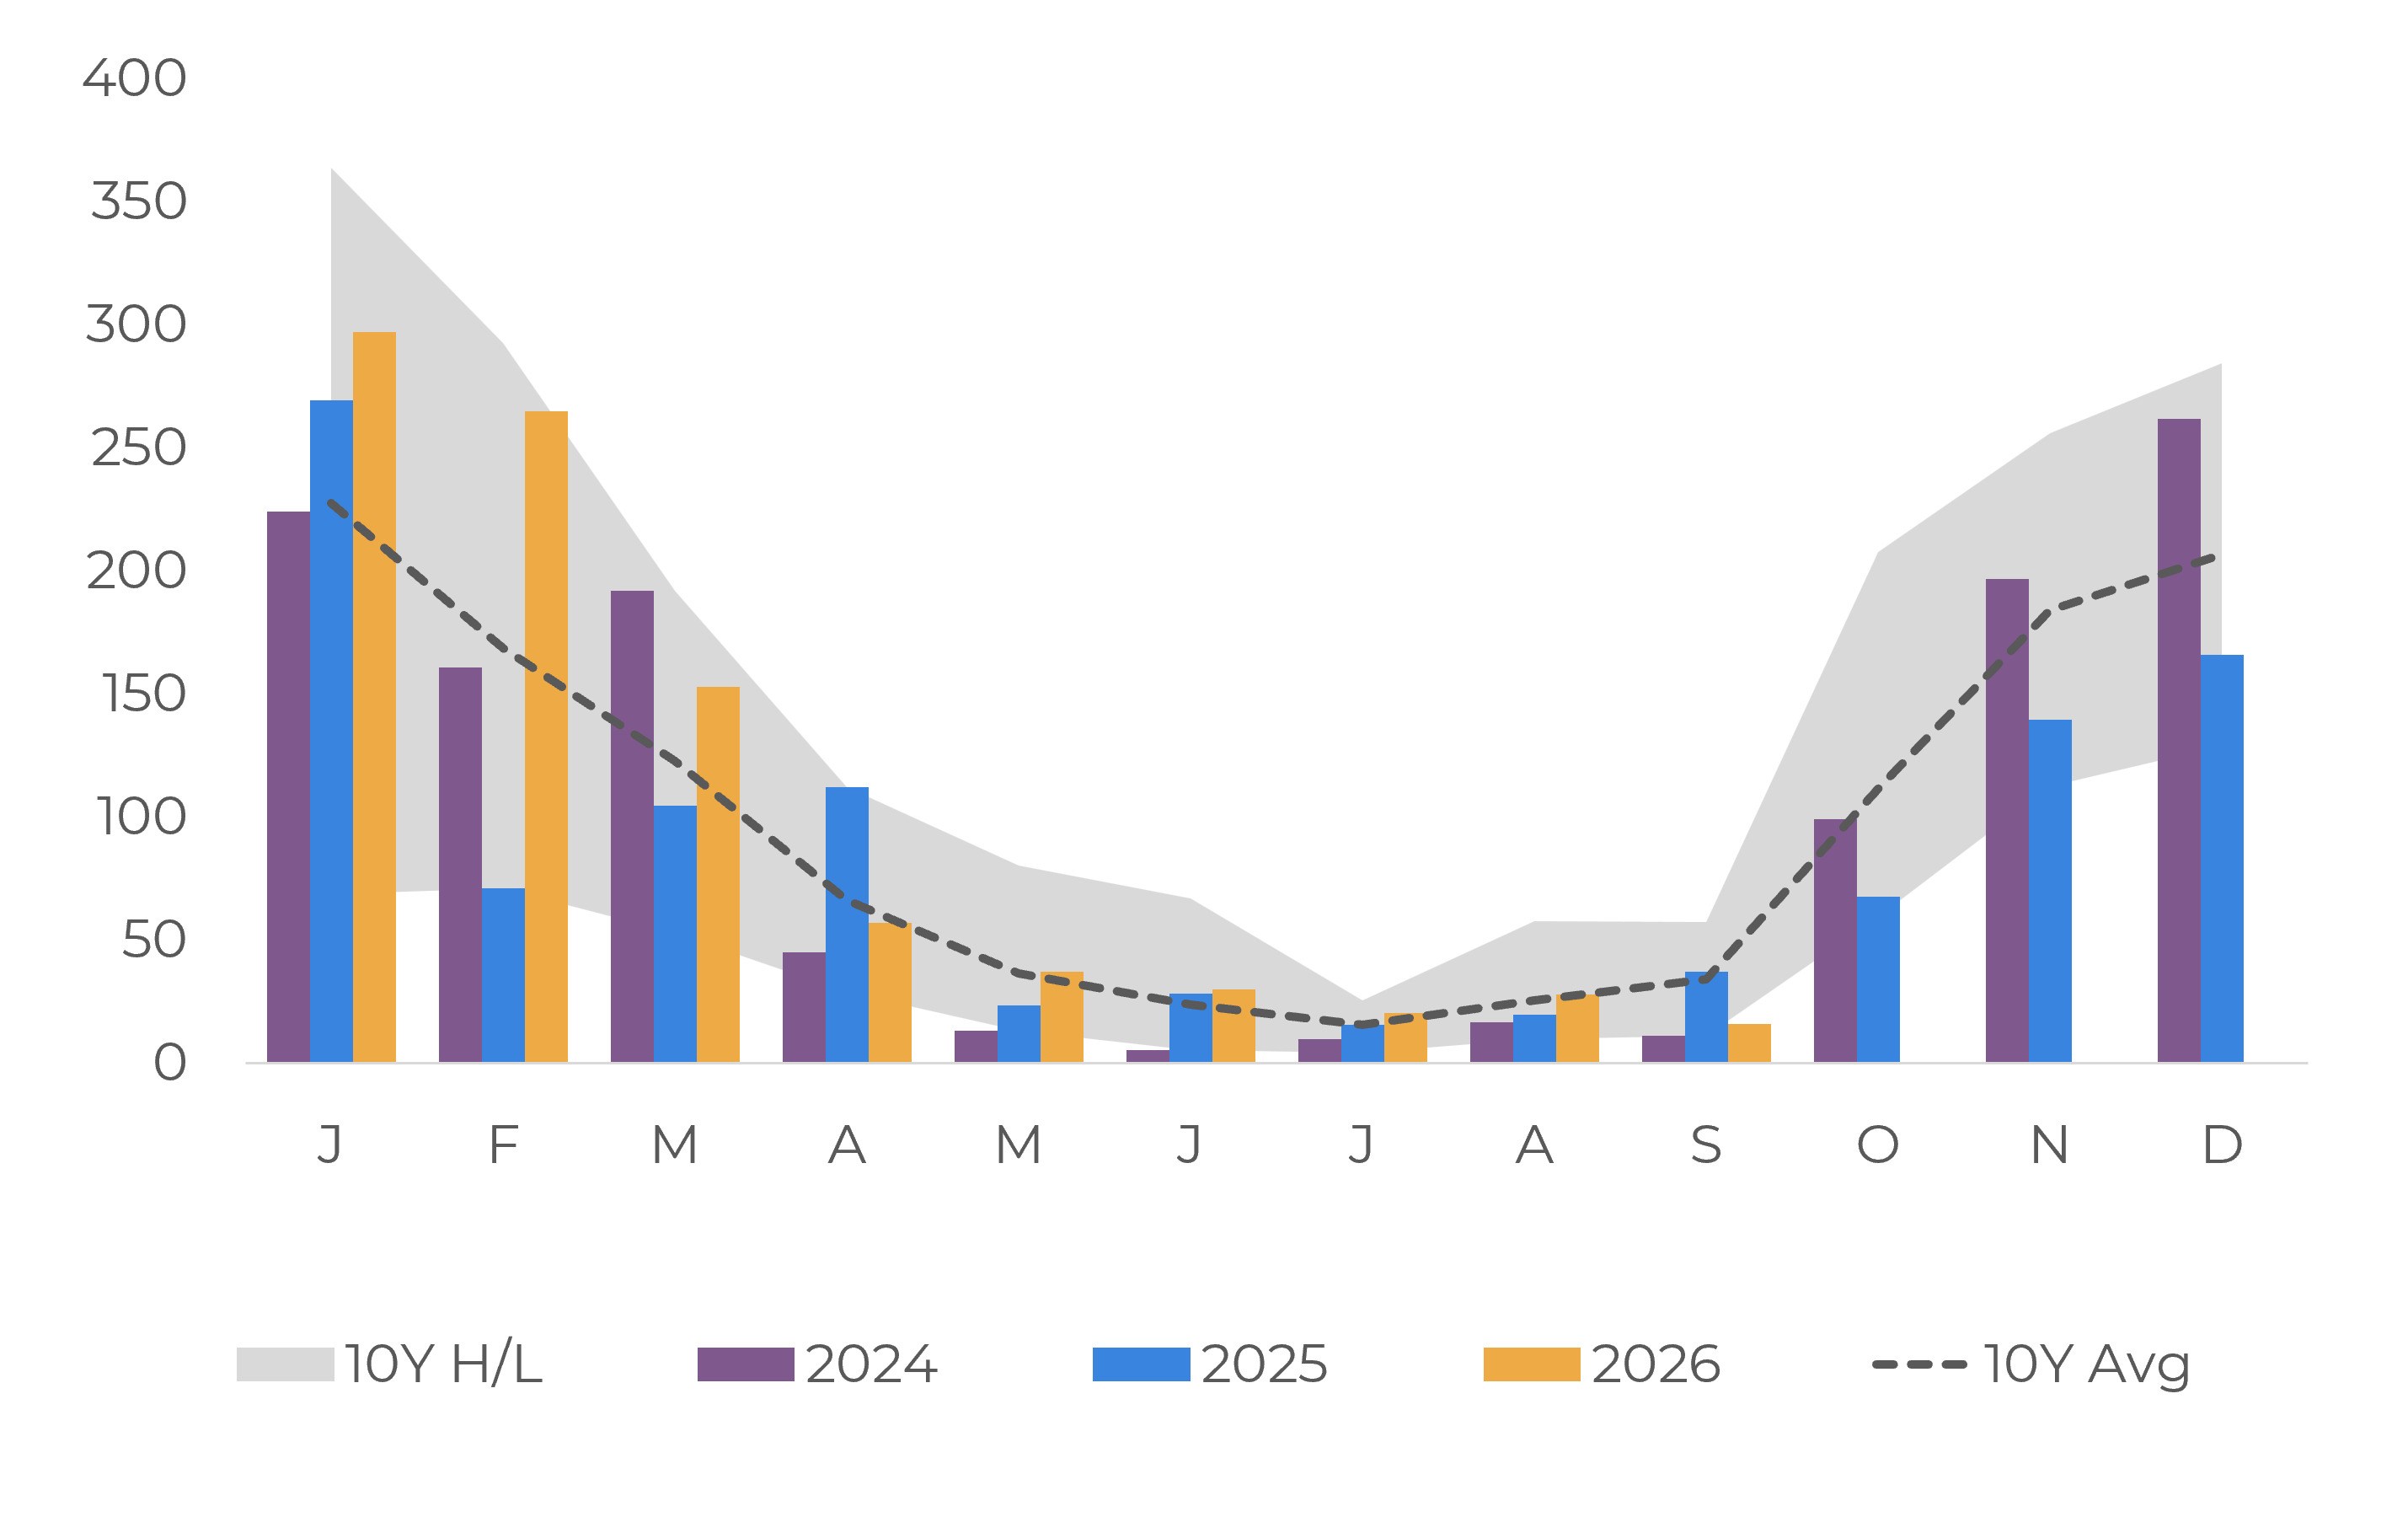
Source: Somar, Bloomberg, Hedgepoint
Precipitation Forecast in Brazil for the next 14 days – European Model (mm)
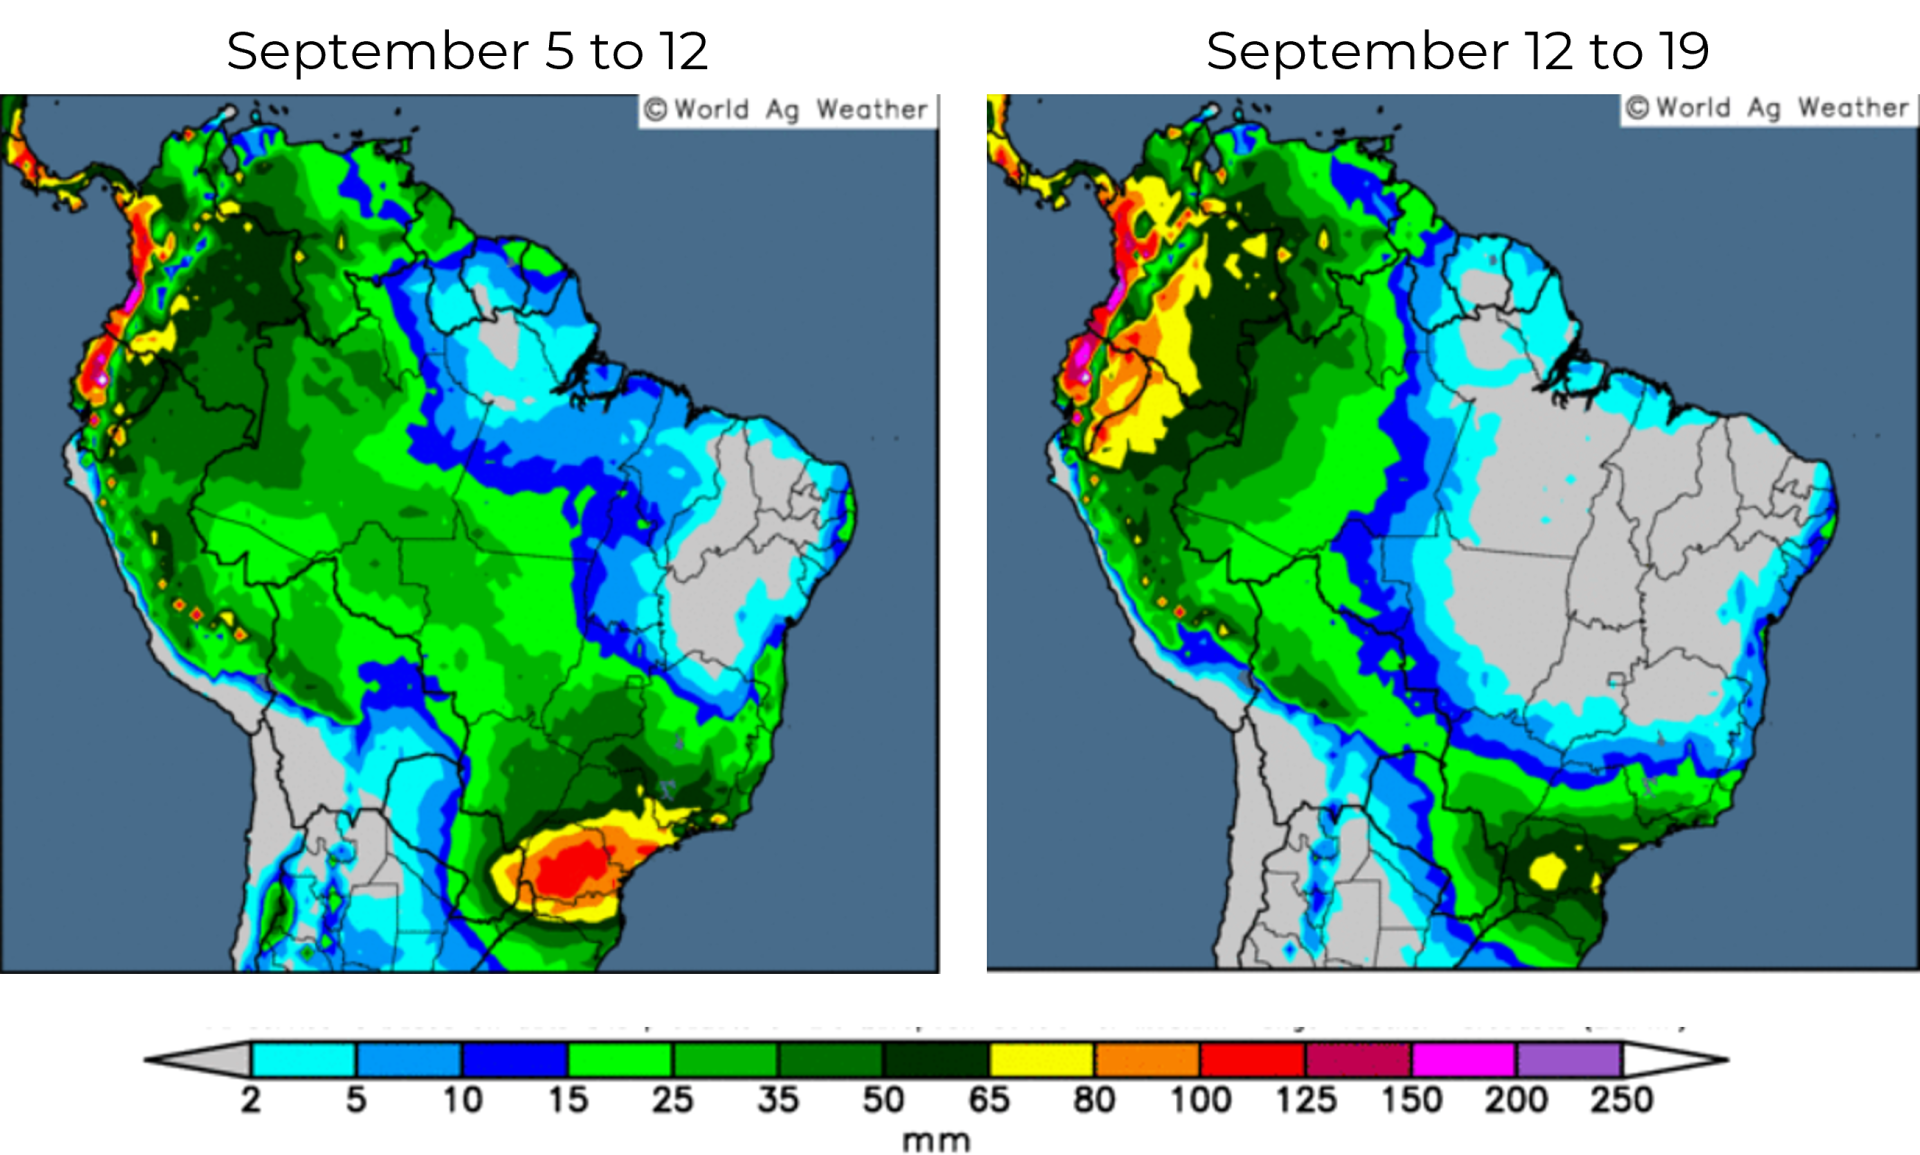
Source: World AG Weather
On the Robusta side, beyond Brazil, Vietnam's export figures are also expected to remain strong in August, according to partial Customs data, reinforcing expectations of ample short-term supply. Robusta certified stocks, unlike Arabica's, have also shown a strong recovery in recent weeks, supported by increased deliveries from Brazil and Indonesia.
However, it's worth mentioning that the RSI is also nearing the oversold zone, which could trigger some covering, especially as the risk of an impact from El Niño still lingers on the horizon and as the Vietnam 2026/27 harvest is expected to gain pace only in late October.
Robusta Certified Stocks (‘000 bags)
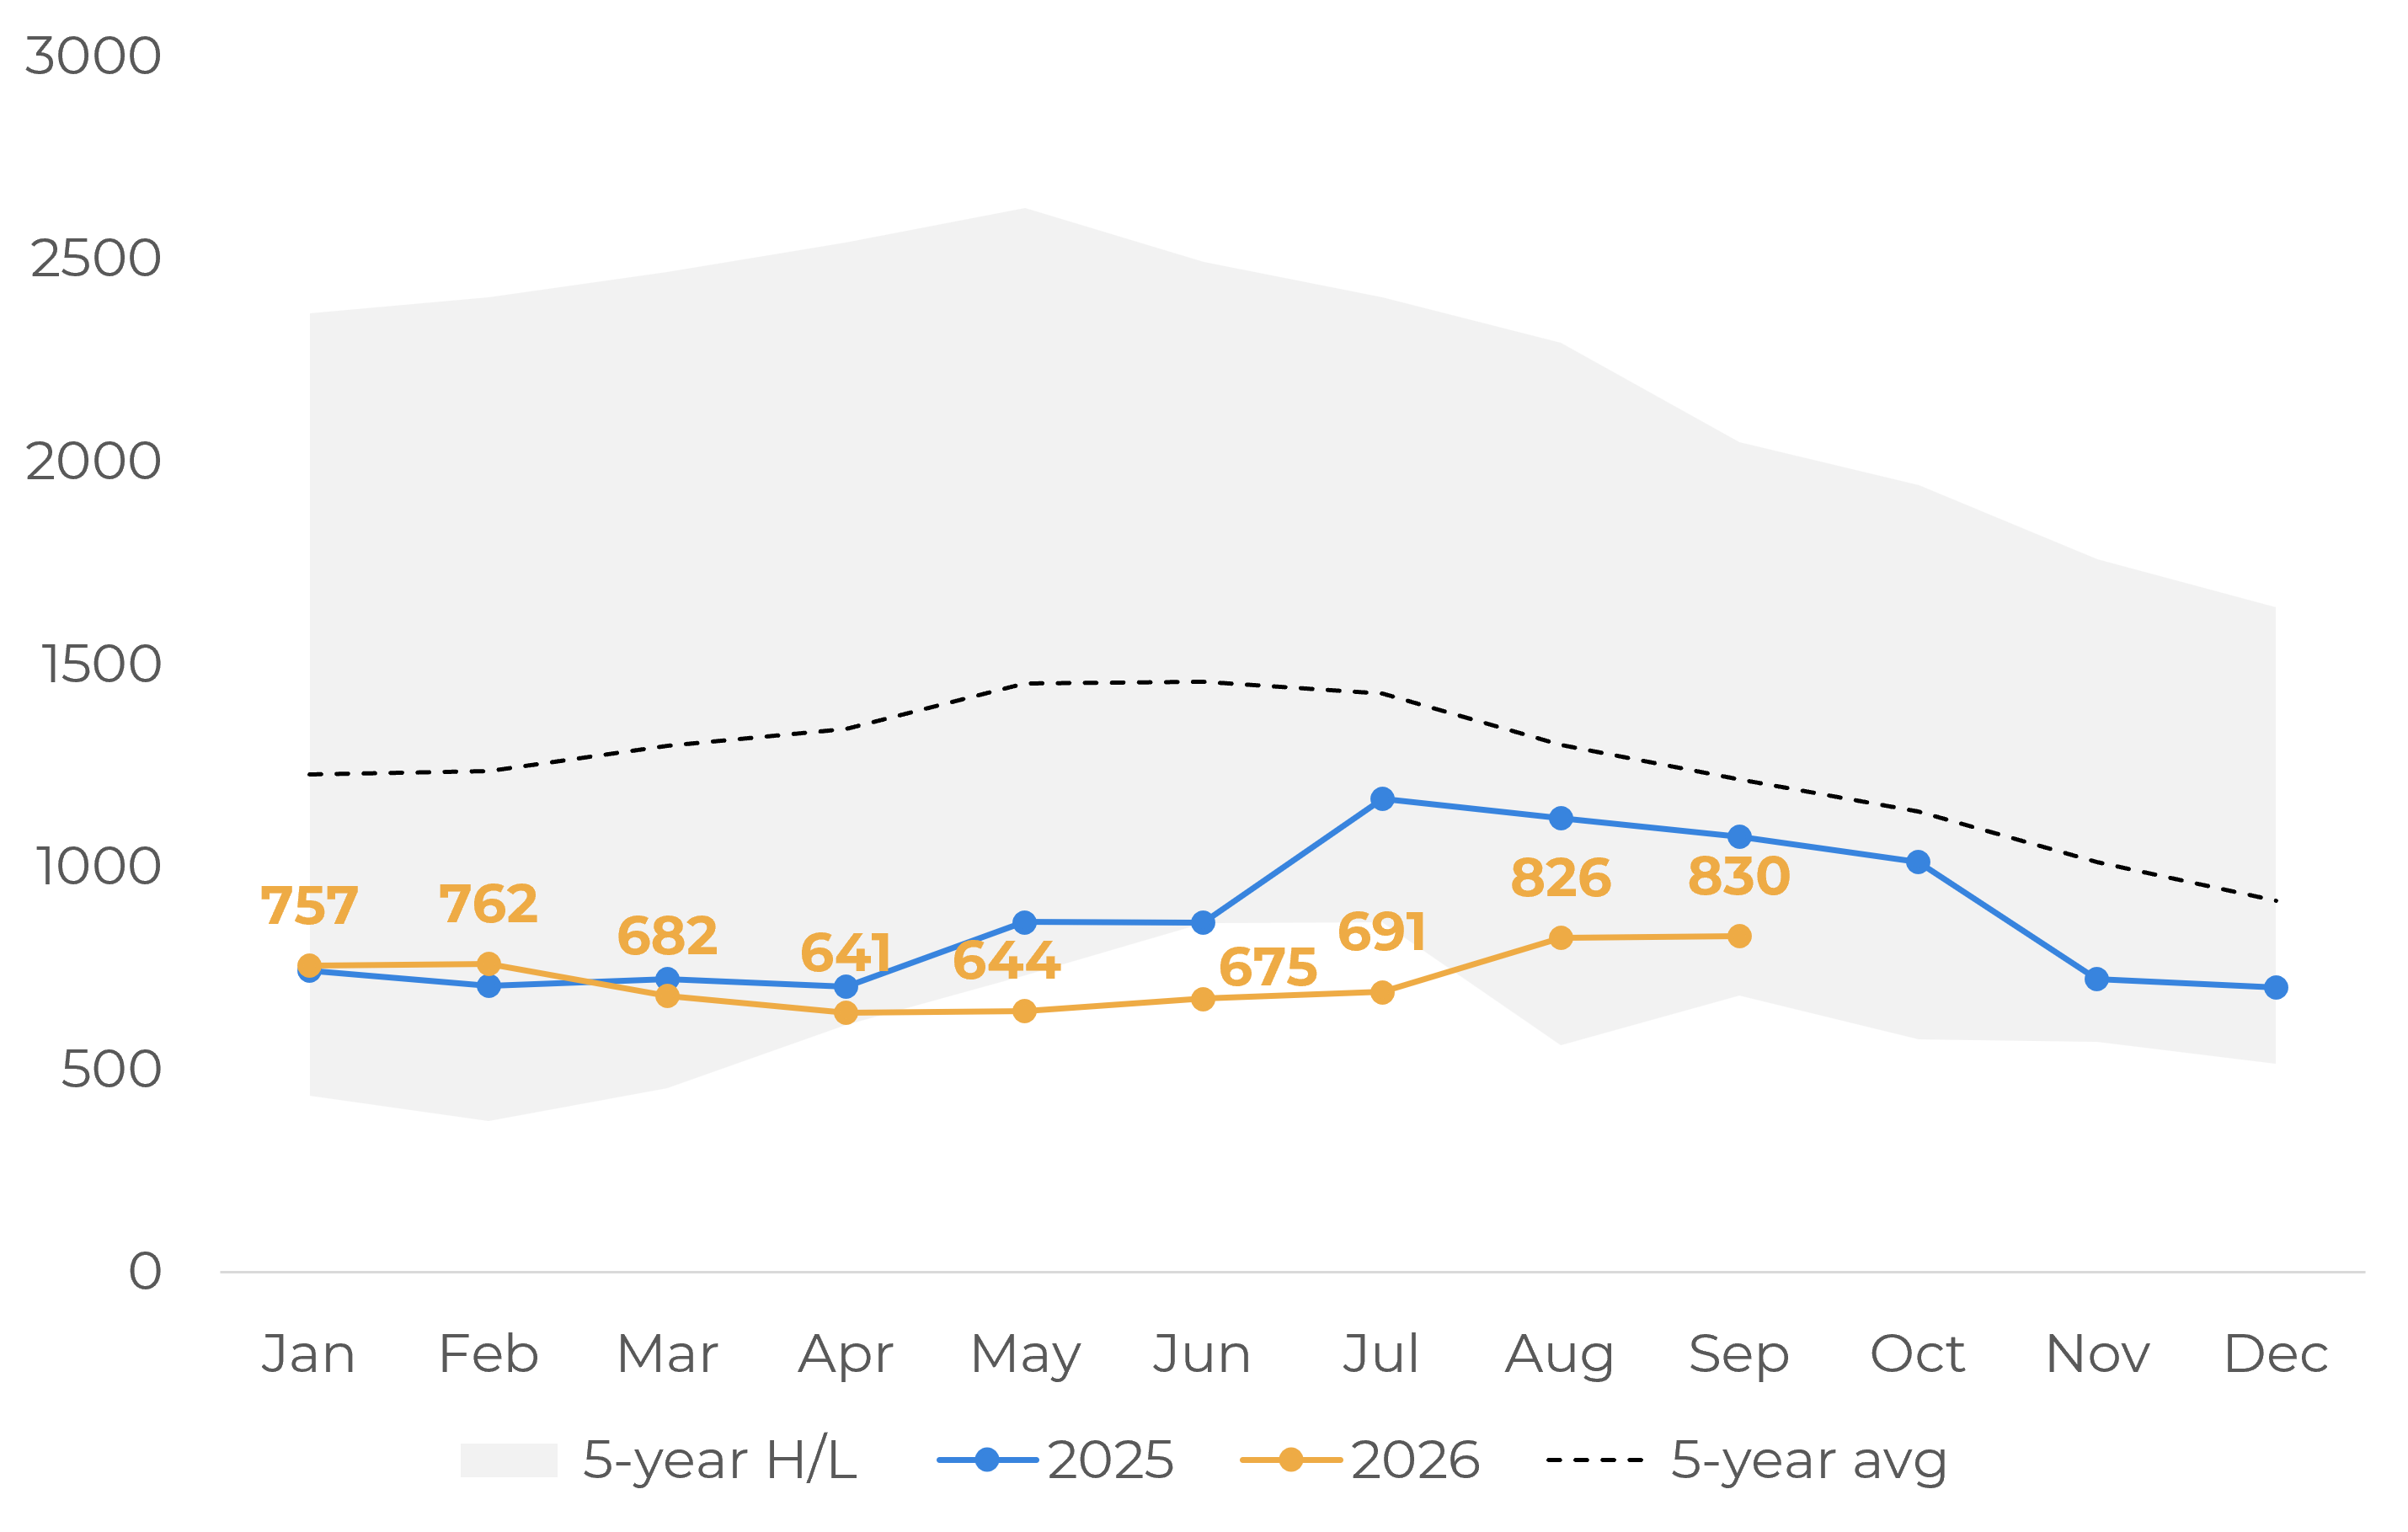
Source: ICE
Macroeconomic developments have also likely contributed to increased volatility across commodity markets, as bond markets recorded significant moves this week. Both 10-year and 30-year government bond yields in major economies, including the United States, Japan, France, Britain, and Germany, rose sharply in recent days, reaching multi-year highs. The move reflects ongoing conflicts in the Middle East, which continue to fuel inflationary concerns, particularly in Europe, as well as growing worries about rising fiscal deficits in the United States and Japan. In the U.S., rising real yields have become increasingly prominent as expanding government debt – now surpassing $40 trillion – coincides with resilient economic growth and bond sales. Besides that, there has been a surge in bond sales to fund AI investments by tech hyperscalers, pushing corporate bonds to a record high and alerting central banks around the world.
For the coffee industry, rising borrowing costs worldwide warrant close attention, as the market structure of recent years has already increased financing costs across the supply chain. Higher yields, particularly in consuming countries, could keep funding and carry costs elevated for roasters, importers, and traders, discouraging inventory rebuilding. With destination stocks remaining relatively low, as observed during the previous season, coffee prices are likely to remain highly sensitive to supply-related developments, suggesting that market volatility could persist in the medium term.
U.S. Treasury bonds
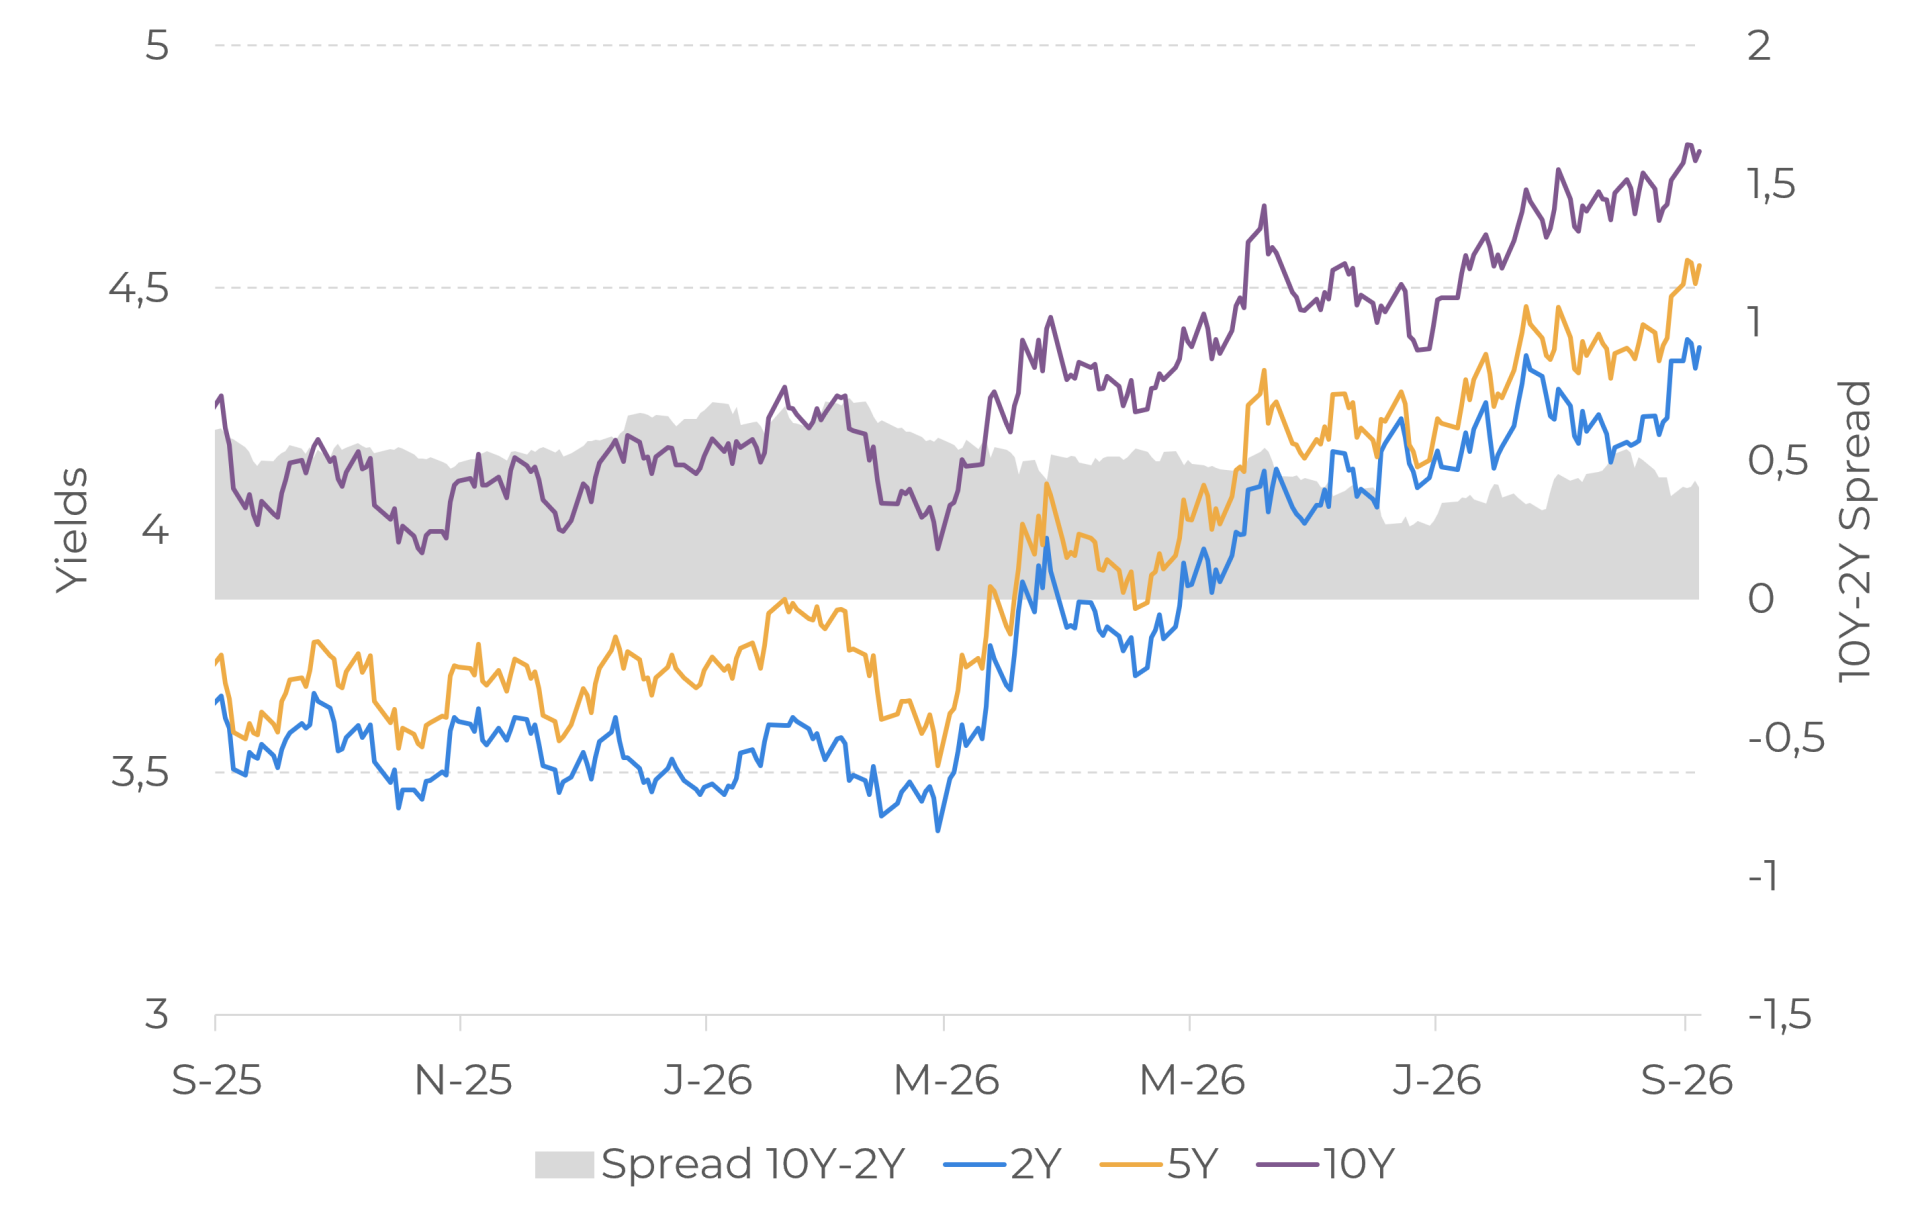
Source: LSEG
In Summary
Weekly Report — Coffee
laleska.moda@hedgepointglobal.com
carolina.franca@hedgepointglobal.com
Disclaimer
This document has been prepared by Hedgepoint Schweiz AG and its affiliates (“Hedgepoint”) solely for informational and instructional purposes, without intending to create obligations or commitments to third parties. It is not intended to promote or solicit an offer for the sale or purchase of any securities, commodities interests, or investment products. Hedgepoint and its associates expressly disclaim any liability for the use of the information contained herein that directly or indirectly results in any kind of damages. Information is obtained from sources which we believe to be reliable, but we do not warrant or guarantee the timeliness or accuracy of this information. The trading of commodities interests, such as futures, options, and swaps, involves substantial risk of loss and may not be suitable for all investors. You should carefully consider wither such trading is suitable for you in light of your financial condition. Past performance is not necessarily indicative of future results. Customers should rely on their own independent judgment and/or consult advisors before entering into any transactions. Hedgepoint does not provide legal, tax or accounting advice and you are responsible for seeking any such advice separately. Hedgepoint Schweiz AG is organized, incorporated, and existing under the laws of Switzerland, is filiated to ARIF, the Association Romande des Intermédiaires Financiers, which is a FINMA-authorized Self-Regulatory Organization. Hedgepoint Commodities LLC is organized, incorporated, and existing under the laws of the USA, and is authorized and regulated by the Commodity Futures Trading Commission (CFTC) and a member of the National Futures Association (NFA) to act as an Introducing Broker and Commodity Trading Advisor. HedgePoint Global Markets Limited is Regulated by the Dubai Financial Services Authority. The content is directed at Professional Clients and not Retail Clients. Hedgepoint Global Markets PTE. Ltd is organized, incorporated, and existing under the laws of Singapore, exempted from obtaining a financial services license as per the Second Schedule of the Securities and Futures (Licensing and Conduct of Business) Act, by the Monetary Authority of Singapore (MAS). Hedgepoint Global Markets DTVM Ltda. is authorized and regulated in Brazil by the Central Bank of Brazil (BCB) and the Brazilian Securities Commission (CVM). Hedgepoint Serviços Ltda. is organized, incorporated, and existing under the laws of Brazil. Hedgepoint Global Markets S.A. is organized, incorporated, and existing under the laws of Uruguay. In case of questions not resolved by the first instance of customer contact (client.services@Hedgepointglobal.com), please contact internal ombudsman channel (ombudsman@hedgepointglobal.com – global or ouvidoria@hedgepointglobal.com – Brazil only) or call 0800-8788408 (Brazil only). Integrity, ethics, and transparency are values that guide our culture. To further strengthen our practices, Hedgepoint has a whistleblower channel for employees and third-parties by e-mail ethicline@hedgepointglobal.com or forms Ethic Line – Hedgepoint Global Markets. “HedgePoint” and the “HedgePoint” logo are marks for the exclusive use of HedgePoint and/or its affiliates. Use or reproduction is prohibited, unless expressly authorized by HedgePoint. Furthermore, the use of any other marks in this document has been authorized for identification purposes only. It does not, therefore, imply any rights of HedgePoint in these marks or imply endorsement, association or seal by the owners of these marks with HedgePoint or its affiliates.