From Tight Supplies to Blooming Prospects
- The Arabica’s December contract has been trading around 280-290 c/lb in recent days, although the overall setup is still bearish, especially given the current Brazilian weather outlook and exports.
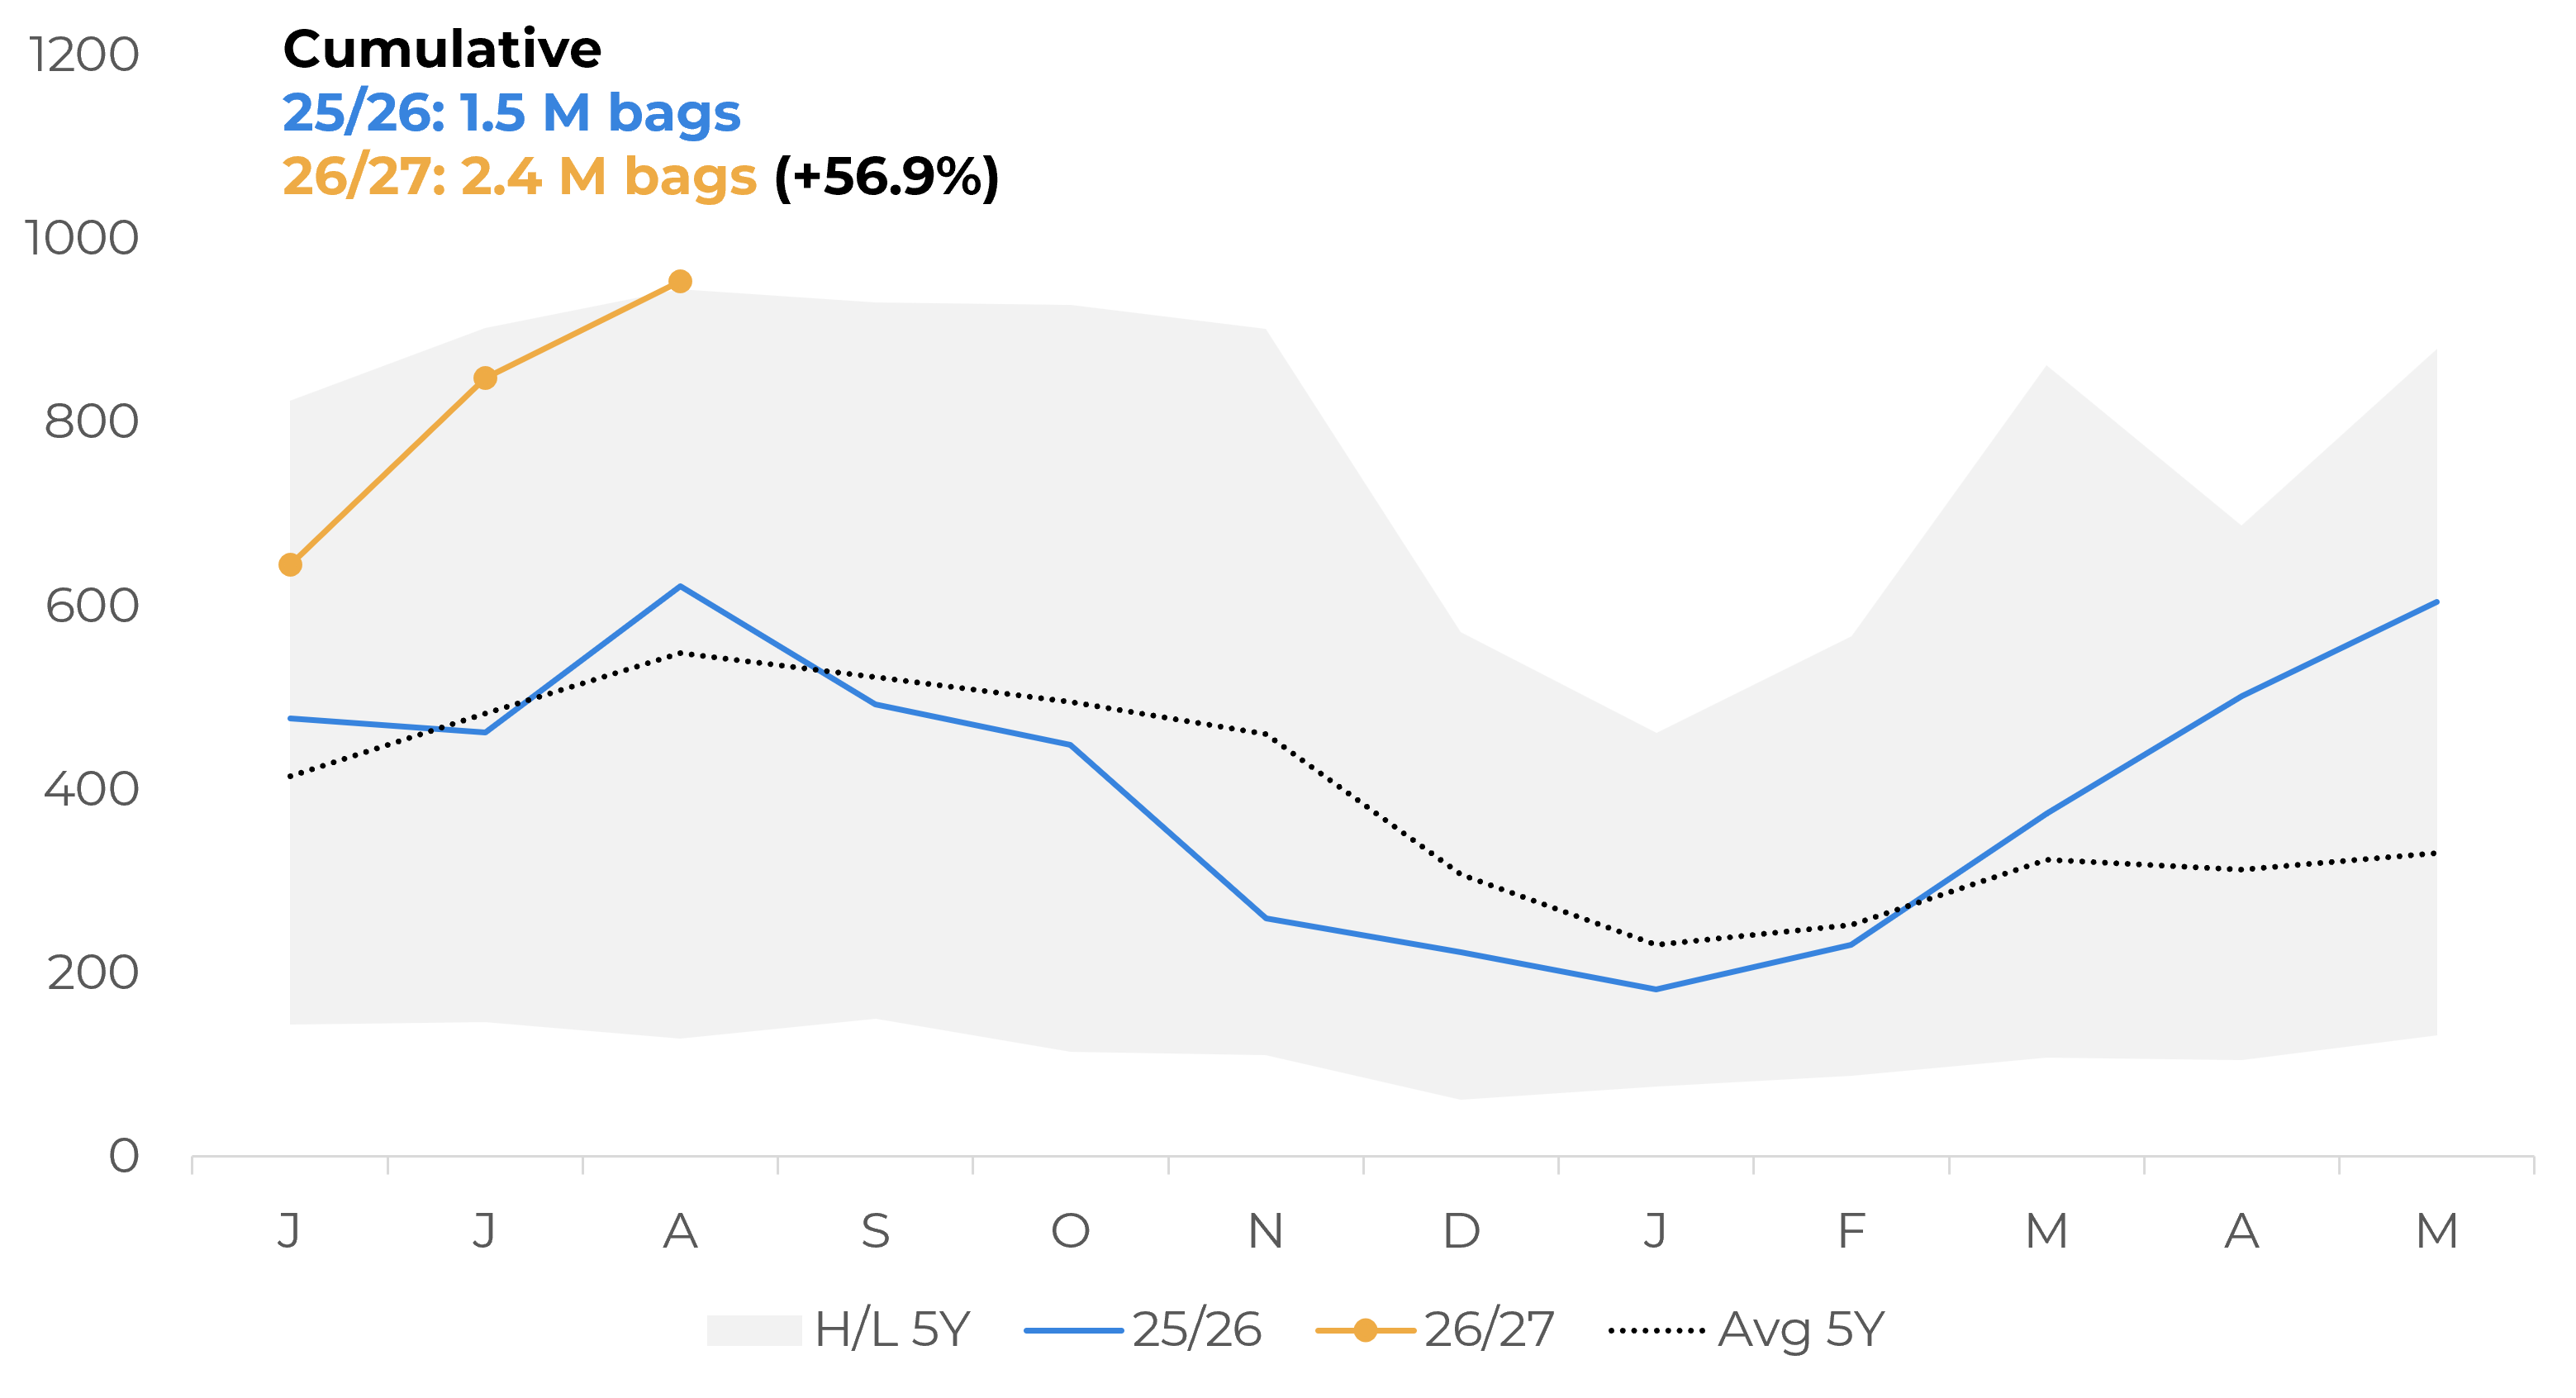
- Brazil's total coffee exports reached 4.16 M bags in August, a new record volume for the month and 31% above the 2025 level. Green coffee shipments totaled 3.8 M bags, also an increase of 31% in one year.
- Weather in the country has also been favorable for the 27/28 season development, with some regions already registering the first flowering of the cycle. September cumulative precipitation has already surpassed the 10-year average.
- On the Rousta side, Vietnam exports continue above average levels in August, helping with the short-term supply outlook, although stocks in the country are now extremely low, likely limiting the next month's shipments. Some farmers expect the 26/27 season harvest to start in early October, but a larger volume of coffee will likely reach the market after November.
From Tight Supplies to Blooming Prospects
Brazil: Arabica Green Coffee Exports (M bags)
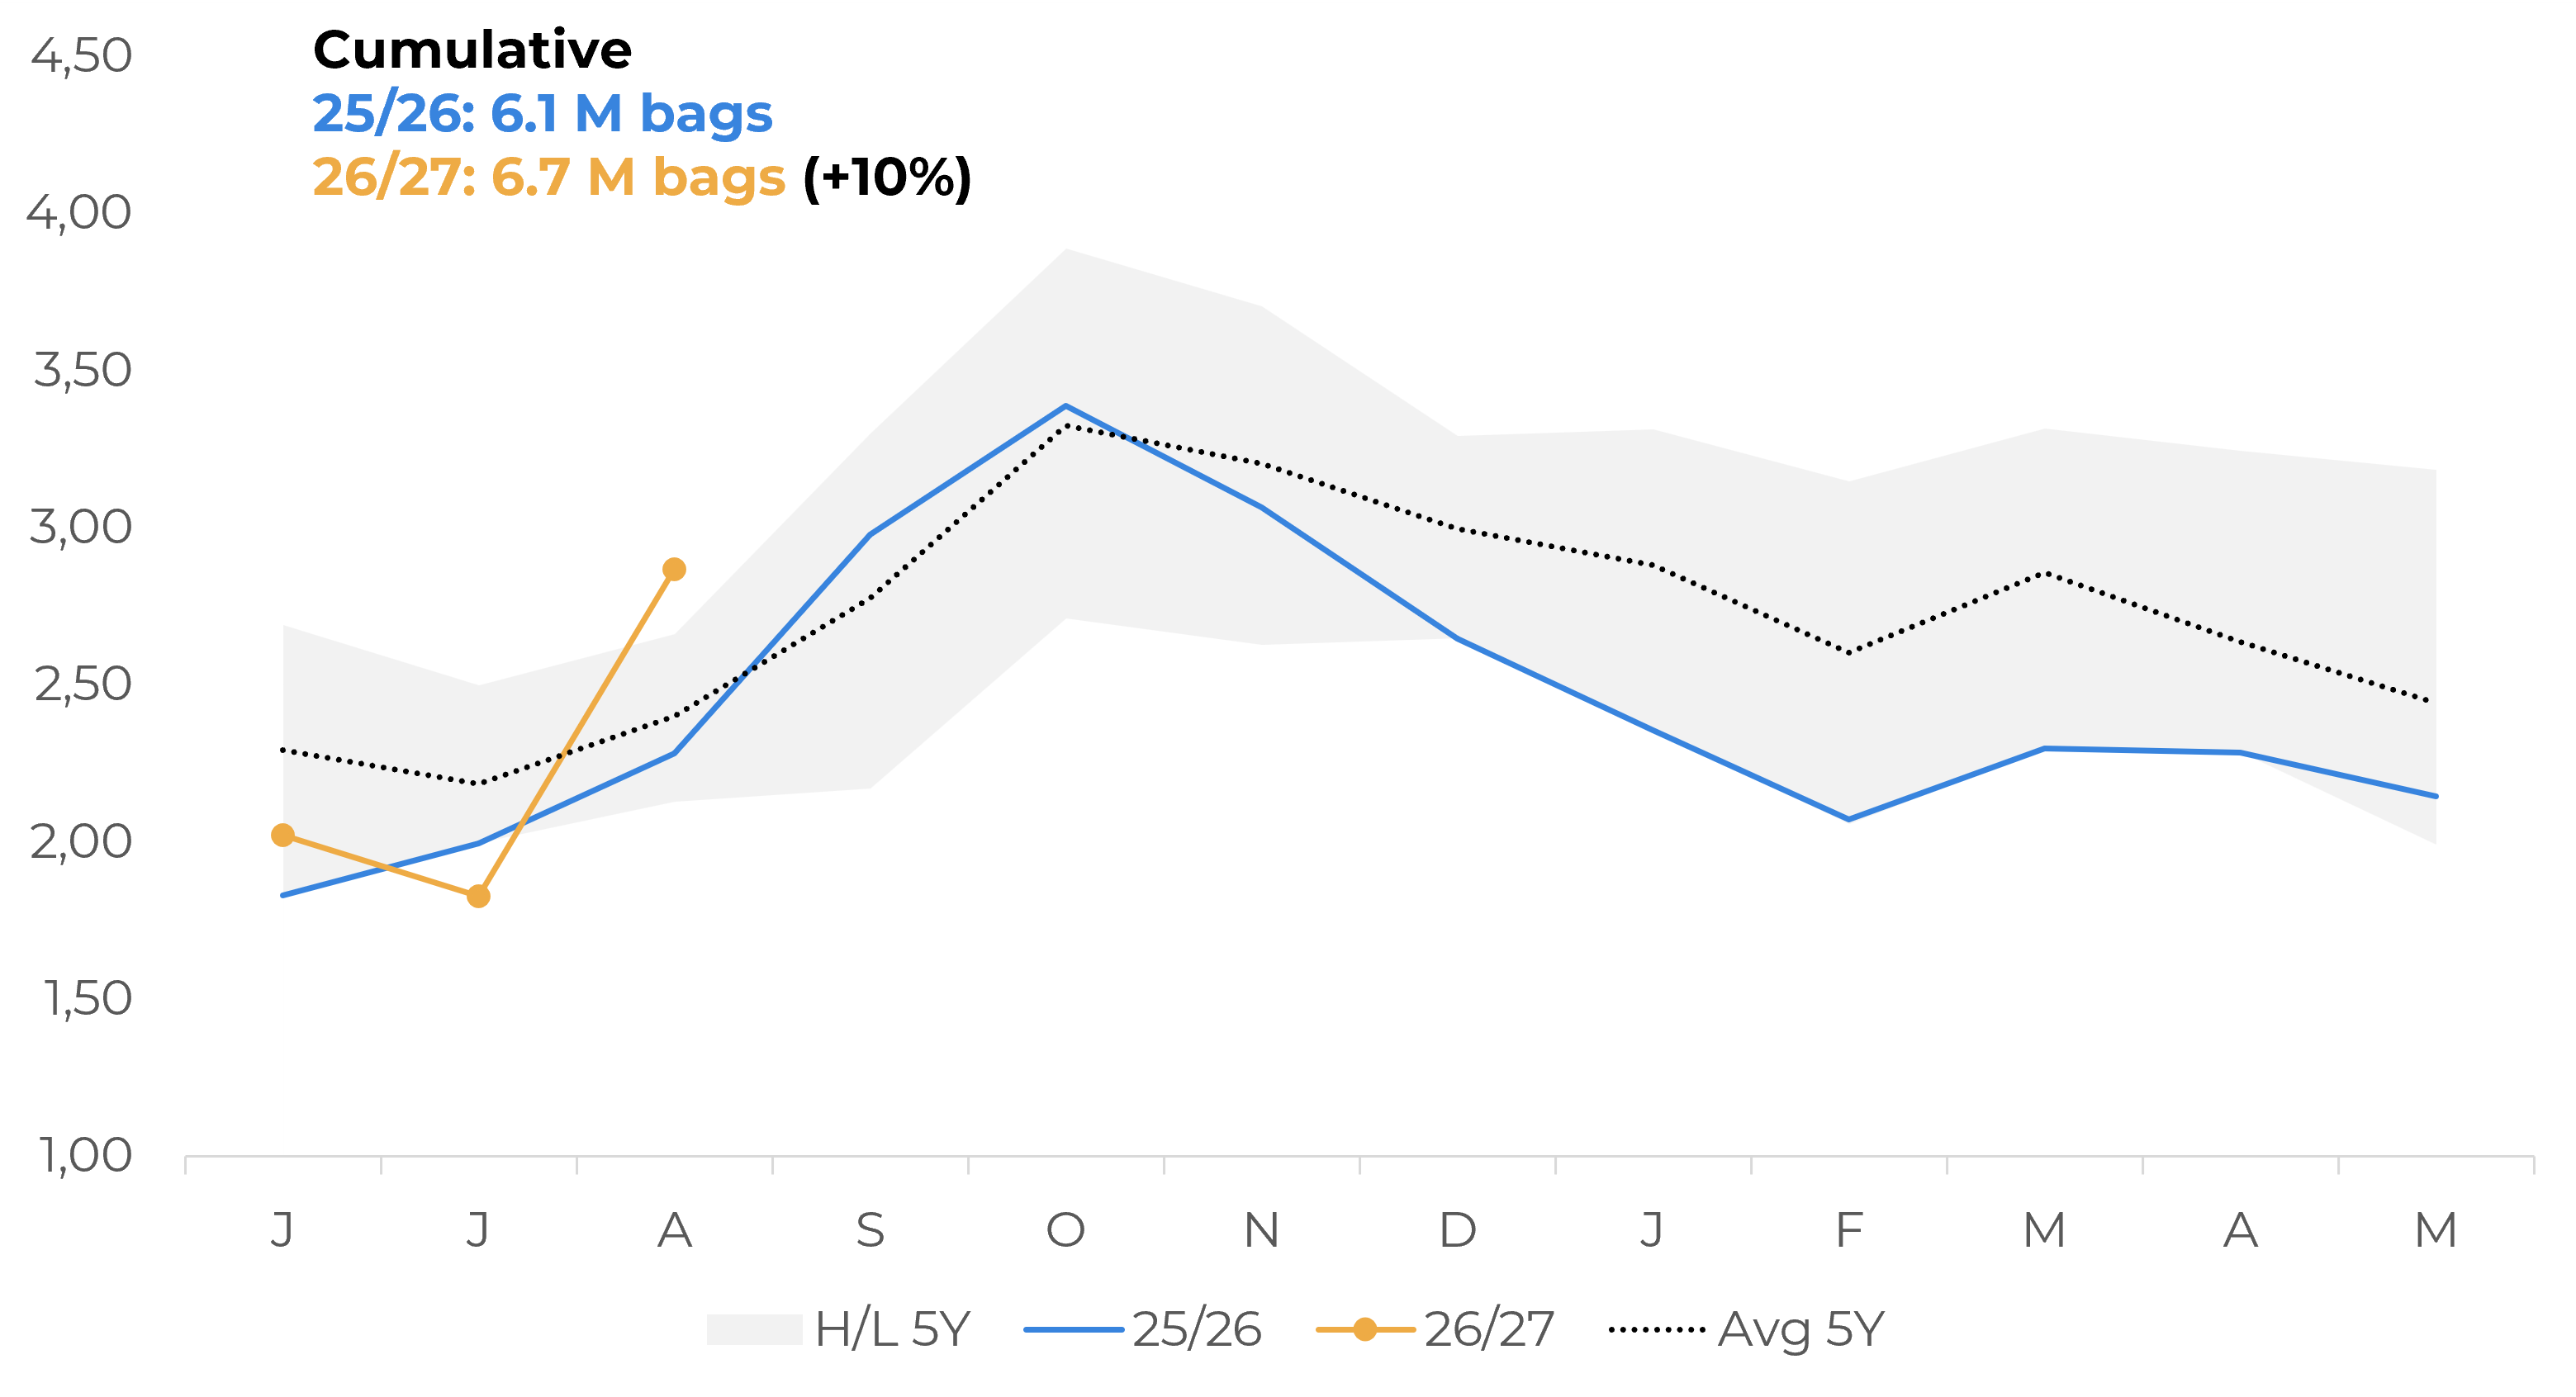
Source: Cecafé
Brazil: Conilon Green Coffee Exports (‘000 bags)
Source: Cecafé
Beyond the increase in exports, with the 26/27 harvest virtually completed by August, market participants shifted their attention to weather conditions and the development of Brazil's 27/28 crop. Since late August, rainfall has reached all producing regions, while partial September accumulations indicate precipitation above the 10-year average across most producing areas, with the exception of Bahia's Highlands and the Atlântico/South region (see the complete report here). This pattern is likely being influenced by El Niño.
Several Arabica and Conilon producing areas have already recorded the first flowering events of the 27/28 season, although a more widespread bloom is still expected across the country. Forecasts indicate continued rainfall through the remainder of September and into October, supporting soil moisture levels and crop development, although excessive precipitation should be closely monitored. While it remains too early to estimate 27/28 production, the expansion of planted area in recent years, combined with favorable weather conditions, is expected to partially offset the negative effects of the Arabica off-year cycle and support output potential. As a result, weather developments over the coming months will be critical for estimating next season's global supply balance.
Cumulative Precipitation in Brazil’s Coffee Regions (mm)
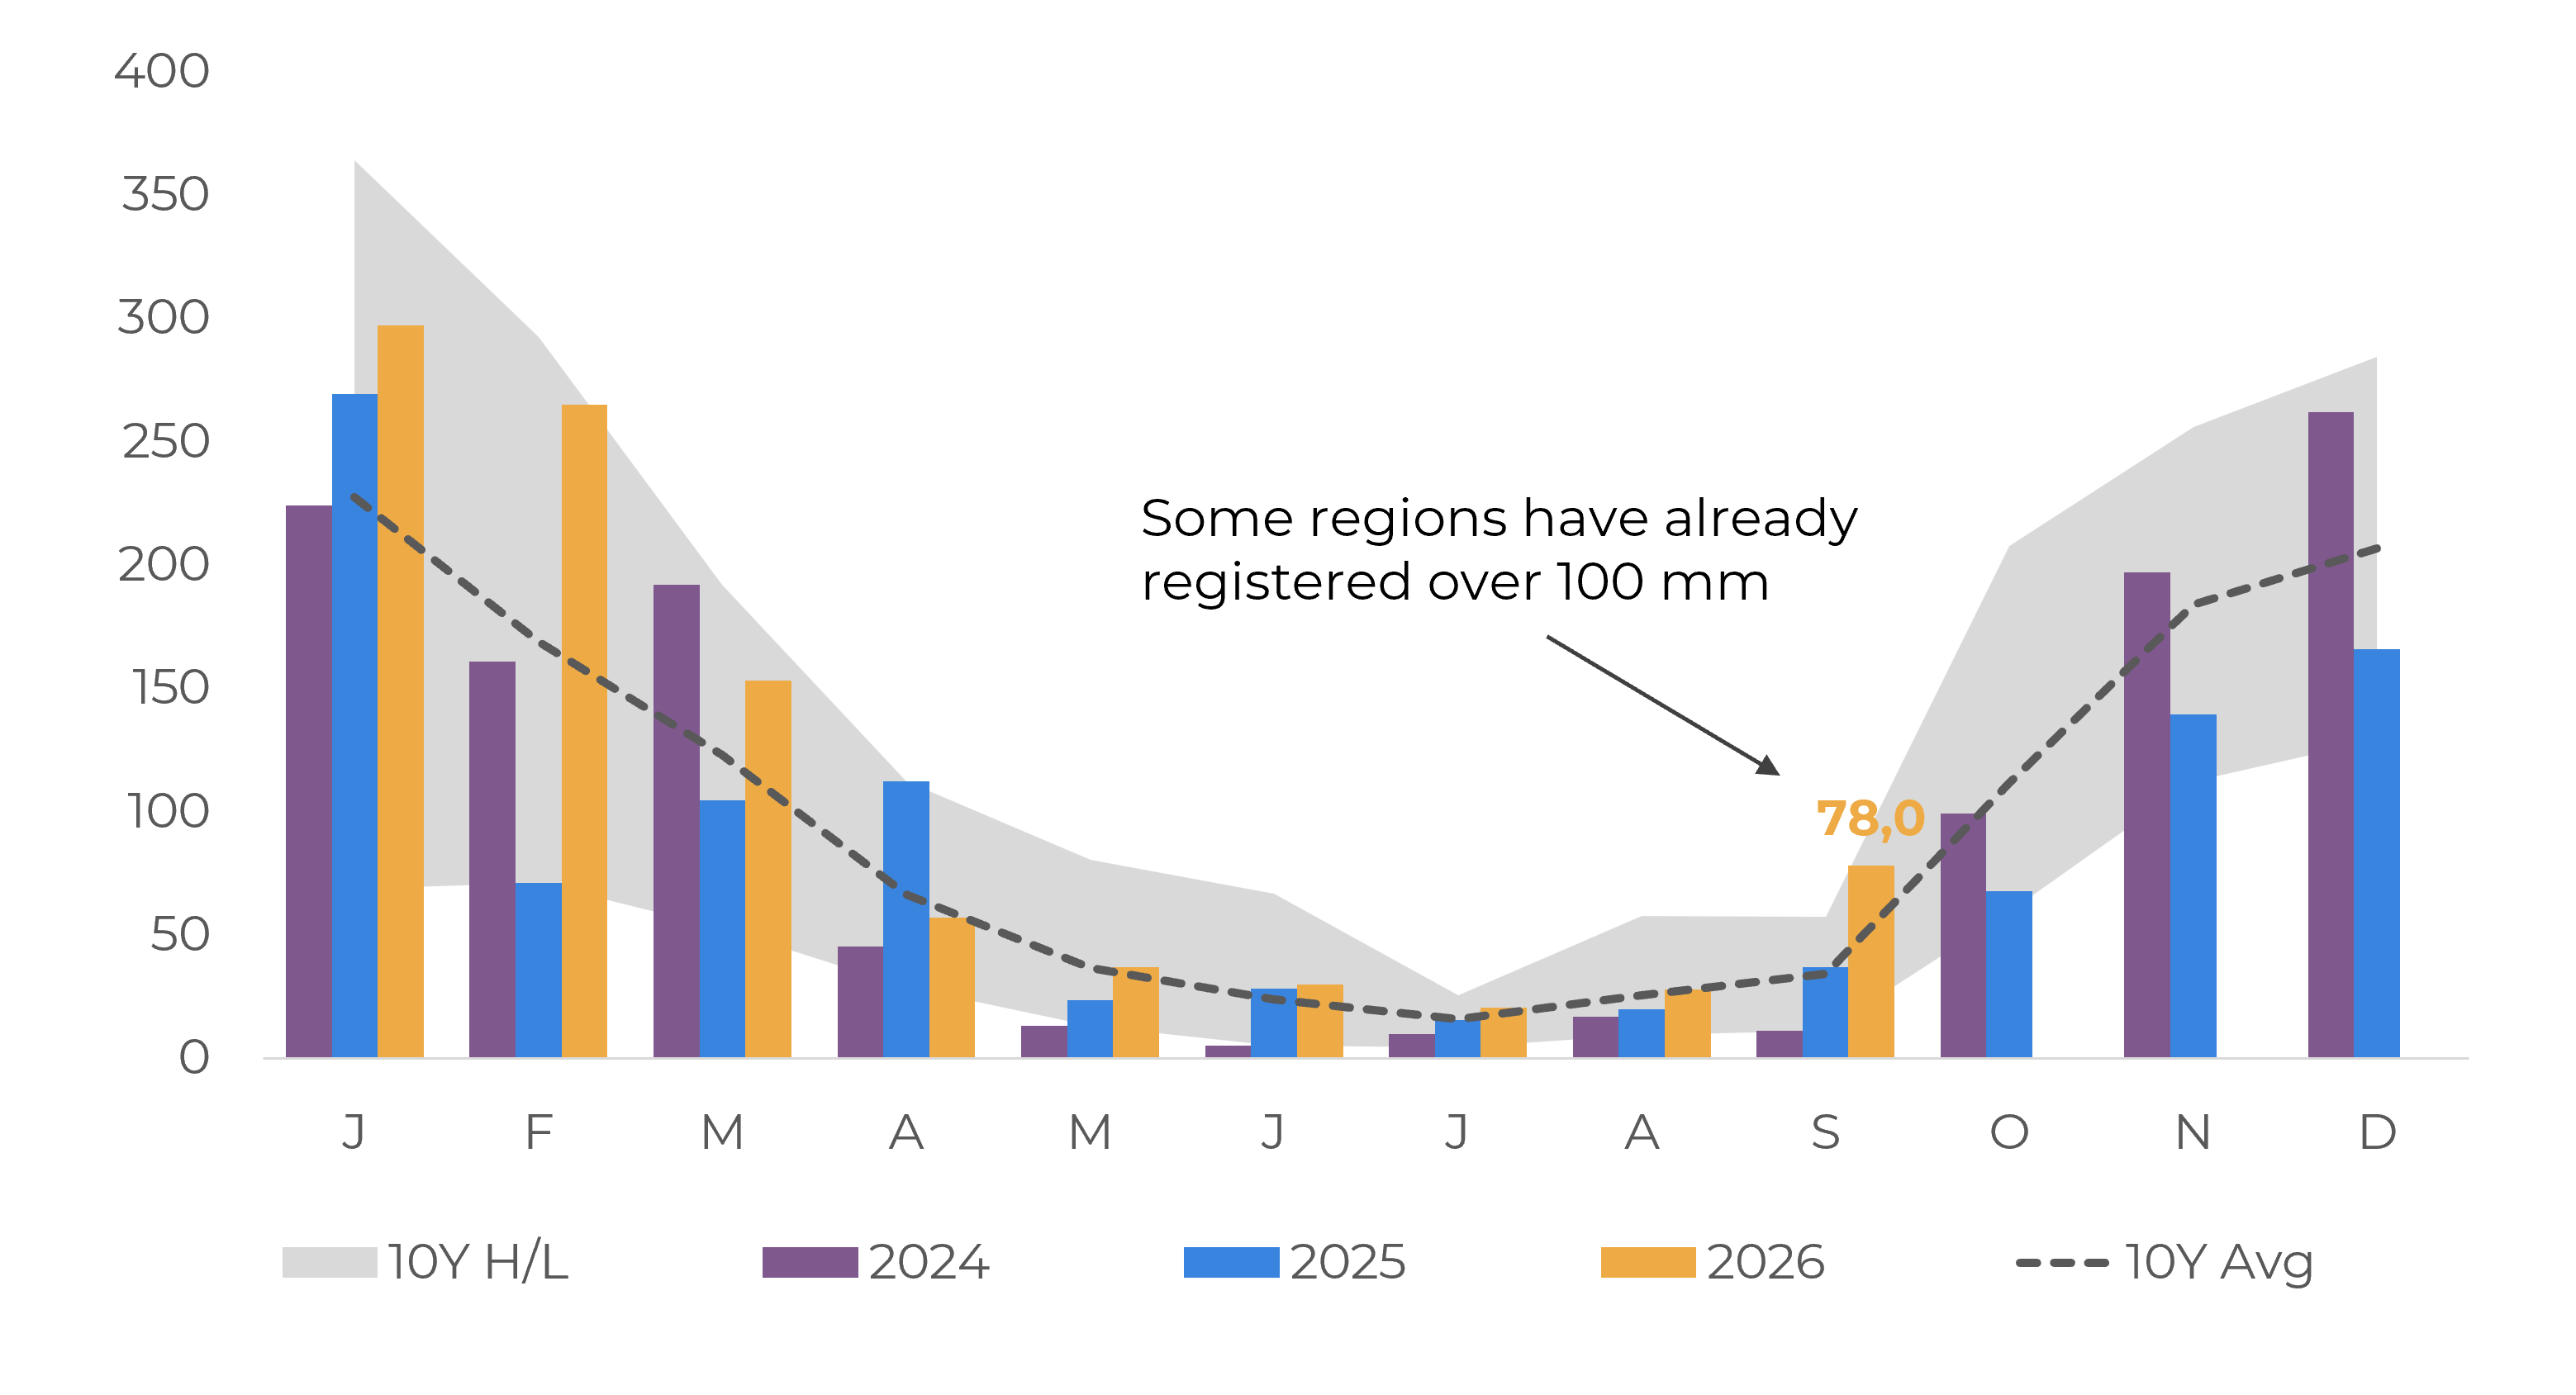
Source: Somar, Bloomberg, Hedgepoint
On the Robusta side, Vietnam exports remained above average in August, supporting the short-term supply outlook. The country exported 2.1 M bags of coffee in August, the highest volume for the month in seven years, reaching a cumulative volume of 27.7 M bags in the 25/26 season (Oct-Aug), an increase of 19.6% versus 24/25 and one of the highest performances in over 7 seasons.
Vietnam: Coffee Exports ('000 bags)
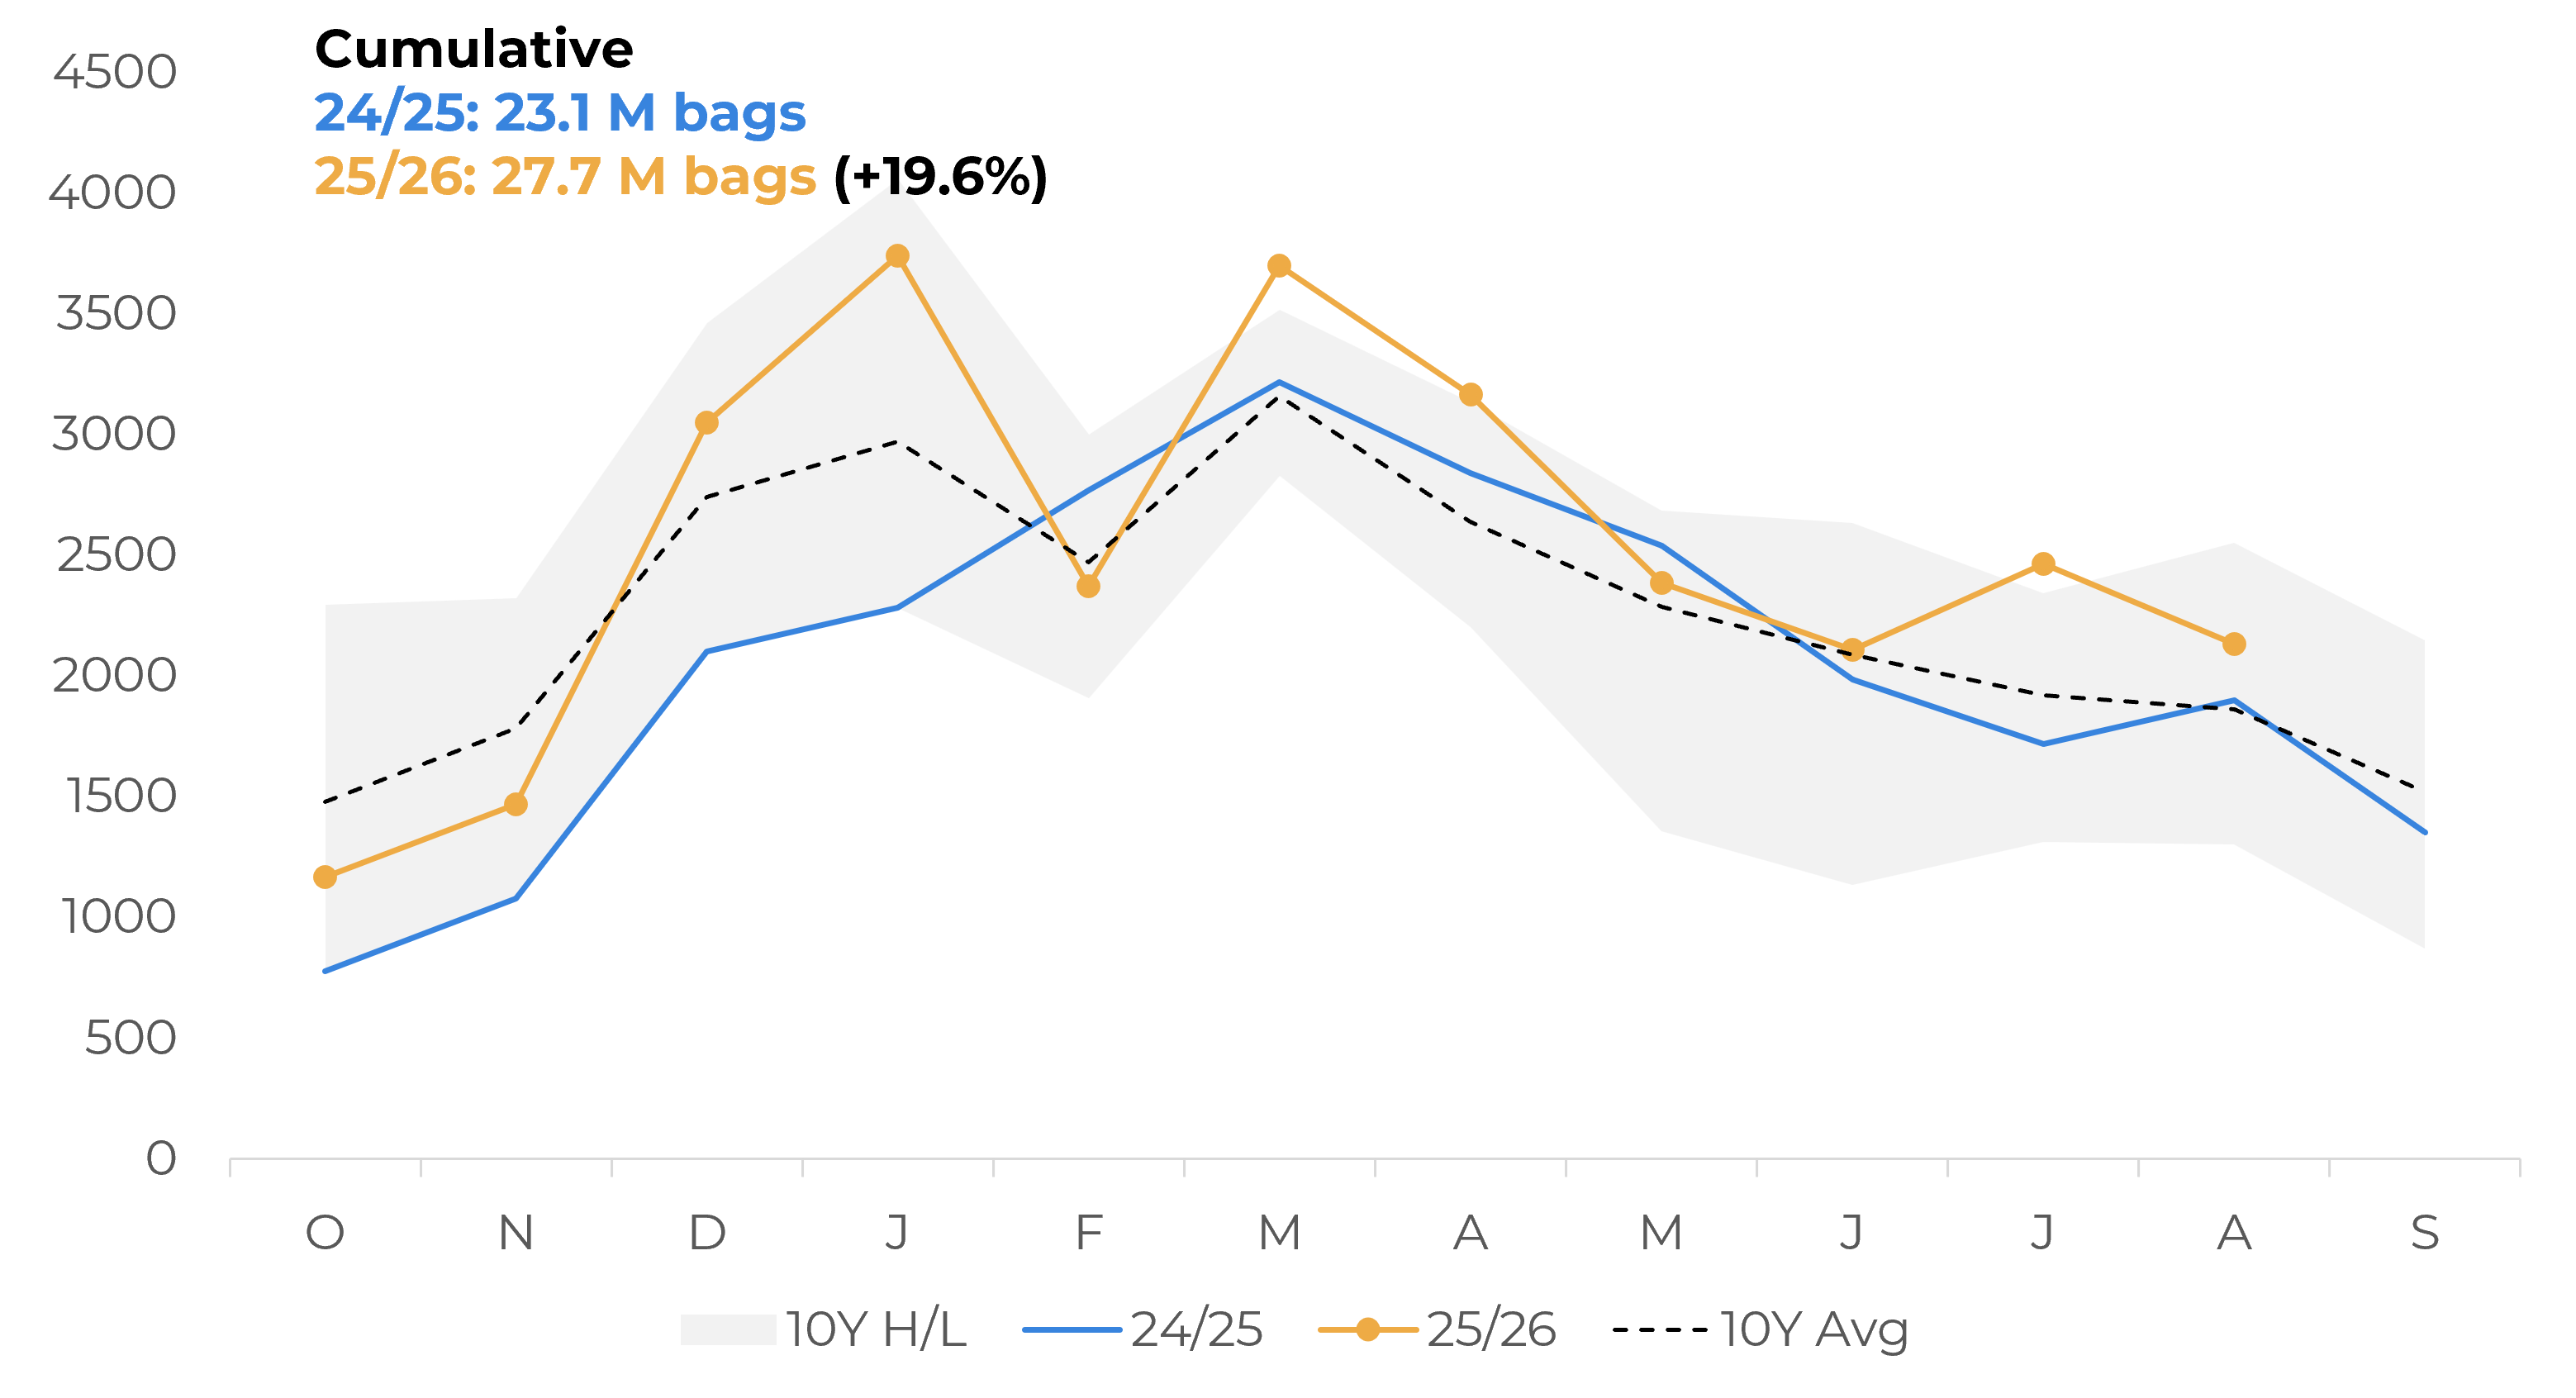
Source: Vietnam Customs
As a result, stocks in the country are now extremely low, likely to limit the next month's shipments. Beyond that, the possible impacts of El Niño still loom on the horizon. Cumulative precipitation in the country has been generally below average since the beginning of the 26/27 crop development, with some regions expecting a decrease in this year's production. However, given the increase in area in recent years, we still estimate production similar to 25/26, at 30.5 M bags. Regarding 26/27 harvest, some farmers are expected to initiate fieldwork in early October, but a larger volume of coffee will likely reach the market only after November.
The El Niño, however, could still affect the 27/28 cycle in Vietnam, especially as the dry season tends to be extended during the phenomenon, decreasing the soil moisture and water availability for irrigation. There is also the risk of the event impacting the Indonesian 27/28 season, which is already under development in the Robusta areas. In this sense, Robusta prices could see some support in the coming months, depending on the impact of El Niño.
Vietnam: Cumulative Precipitation in Central Highlands (mm)
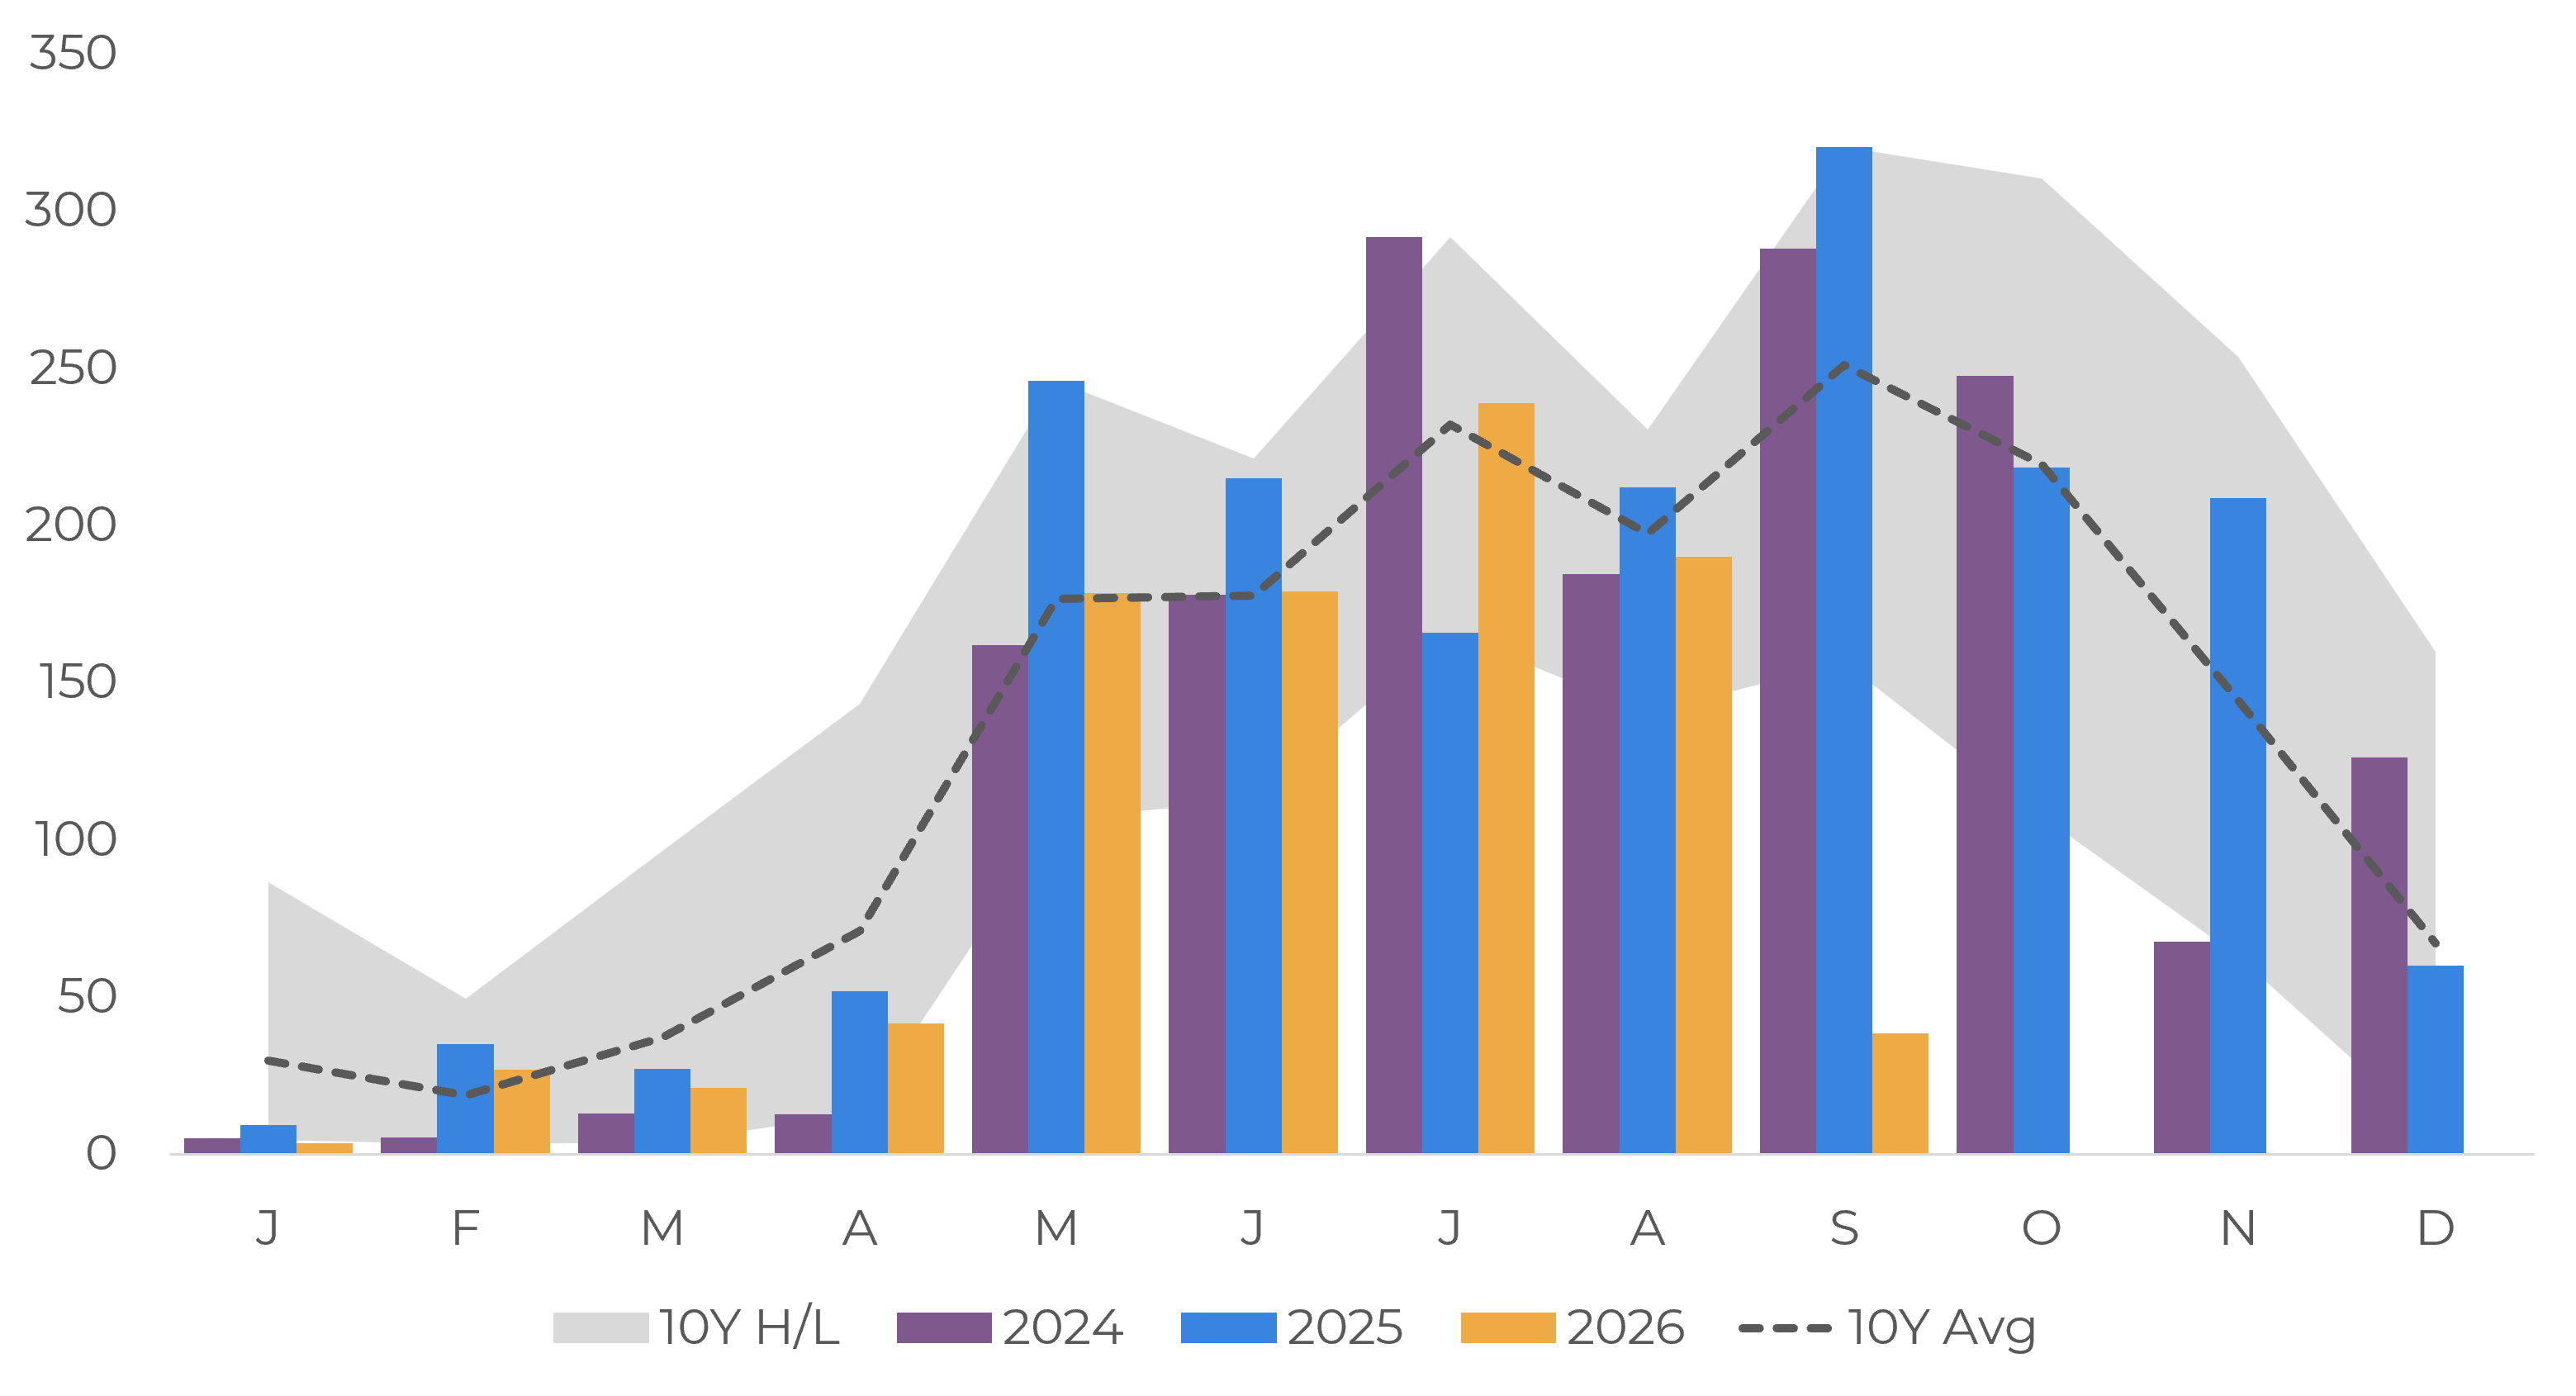
Source: Google Earth, Copernicus, Hedgepoint
In Summary
Weekly Report — Coffee
laleska.moda@hedgepointglobal.com
livea.coda@hedgepointglobal.com
Disclaimer
This document has been prepared by Hedgepoint Schweiz AG and its affiliates (“Hedgepoint”) solely for informational and instructional purposes, without intending to create obligations or commitments to third parties. It is not intended to promote or solicit an offer for the sale or purchase of any securities, commodities interests, or investment products. Hedgepoint and its associates expressly disclaim any liability for the use of the information contained herein that directly or indirectly results in any kind of damages. Information is obtained from sources which we believe to be reliable, but we do not warrant or guarantee the timeliness or accuracy of this information. The trading of commodities interests, such as futures, options, and swaps, involves substantial risk of loss and may not be suitable for all investors. You should carefully consider wither such trading is suitable for you in light of your financial condition. Past performance is not necessarily indicative of future results. Customers should rely on their own independent judgment and/or consult advisors before entering into any transactions. Hedgepoint does not provide legal, tax or accounting advice and you are responsible for seeking any such advice separately. Hedgepoint Schweiz AG is organized, incorporated, and existing under the laws of Switzerland, is filiated to ARIF, the Association Romande des Intermédiaires Financiers, which is a FINMA-authorized Self-Regulatory Organization. Hedgepoint Commodities LLC is organized, incorporated, and existing under the laws of the USA, and is authorized and regulated by the Commodity Futures Trading Commission (CFTC) and a member of the National Futures Association (NFA) to act as an Introducing Broker and Commodity Trading Advisor. HedgePoint Global Markets Limited is Regulated by the Dubai Financial Services Authority. The content is directed at Professional Clients and not Retail Clients. Hedgepoint Global Markets PTE. Ltd is organized, incorporated, and existing under the laws of Singapore, exempted from obtaining a financial services license as per the Second Schedule of the Securities and Futures (Licensing and Conduct of Business) Act, by the Monetary Authority of Singapore (MAS). Hedgepoint Global Markets DTVM Ltda. is authorized and regulated in Brazil by the Central Bank of Brazil (BCB) and the Brazilian Securities Commission (CVM). Hedgepoint Serviços Ltda. is organized, incorporated, and existing under the laws of Brazil. Hedgepoint Global Markets S.A. is organized, incorporated, and existing under the laws of Uruguay. In case of questions not resolved by the first instance of customer contact (client.services@Hedgepointglobal.com), please contact internal ombudsman channel (ombudsman@hedgepointglobal.com – global or ouvidoria@hedgepointglobal.com – Brazil only) or call 0800-8788408 (Brazil only). Integrity, ethics, and transparency are values that guide our culture. To further strengthen our practices, Hedgepoint has a whistleblower channel for employees and third-parties by e-mail ethicline@hedgepointglobal.com or forms Ethic Line – Hedgepoint Global Markets. “HedgePoint” and the “HedgePoint” logo are marks for the exclusive use of HedgePoint and/or its affiliates. Use or reproduction is prohibited, unless expressly authorized by HedgePoint. Furthermore, the use of any other marks in this document has been authorized for identification purposes only. It does not, therefore, imply any rights of HedgePoint in these marks or imply endorsement, association or seal by the owners of these marks with HedgePoint or its affiliates.