Coffee Markets Ease as Supply Pressure Mounts
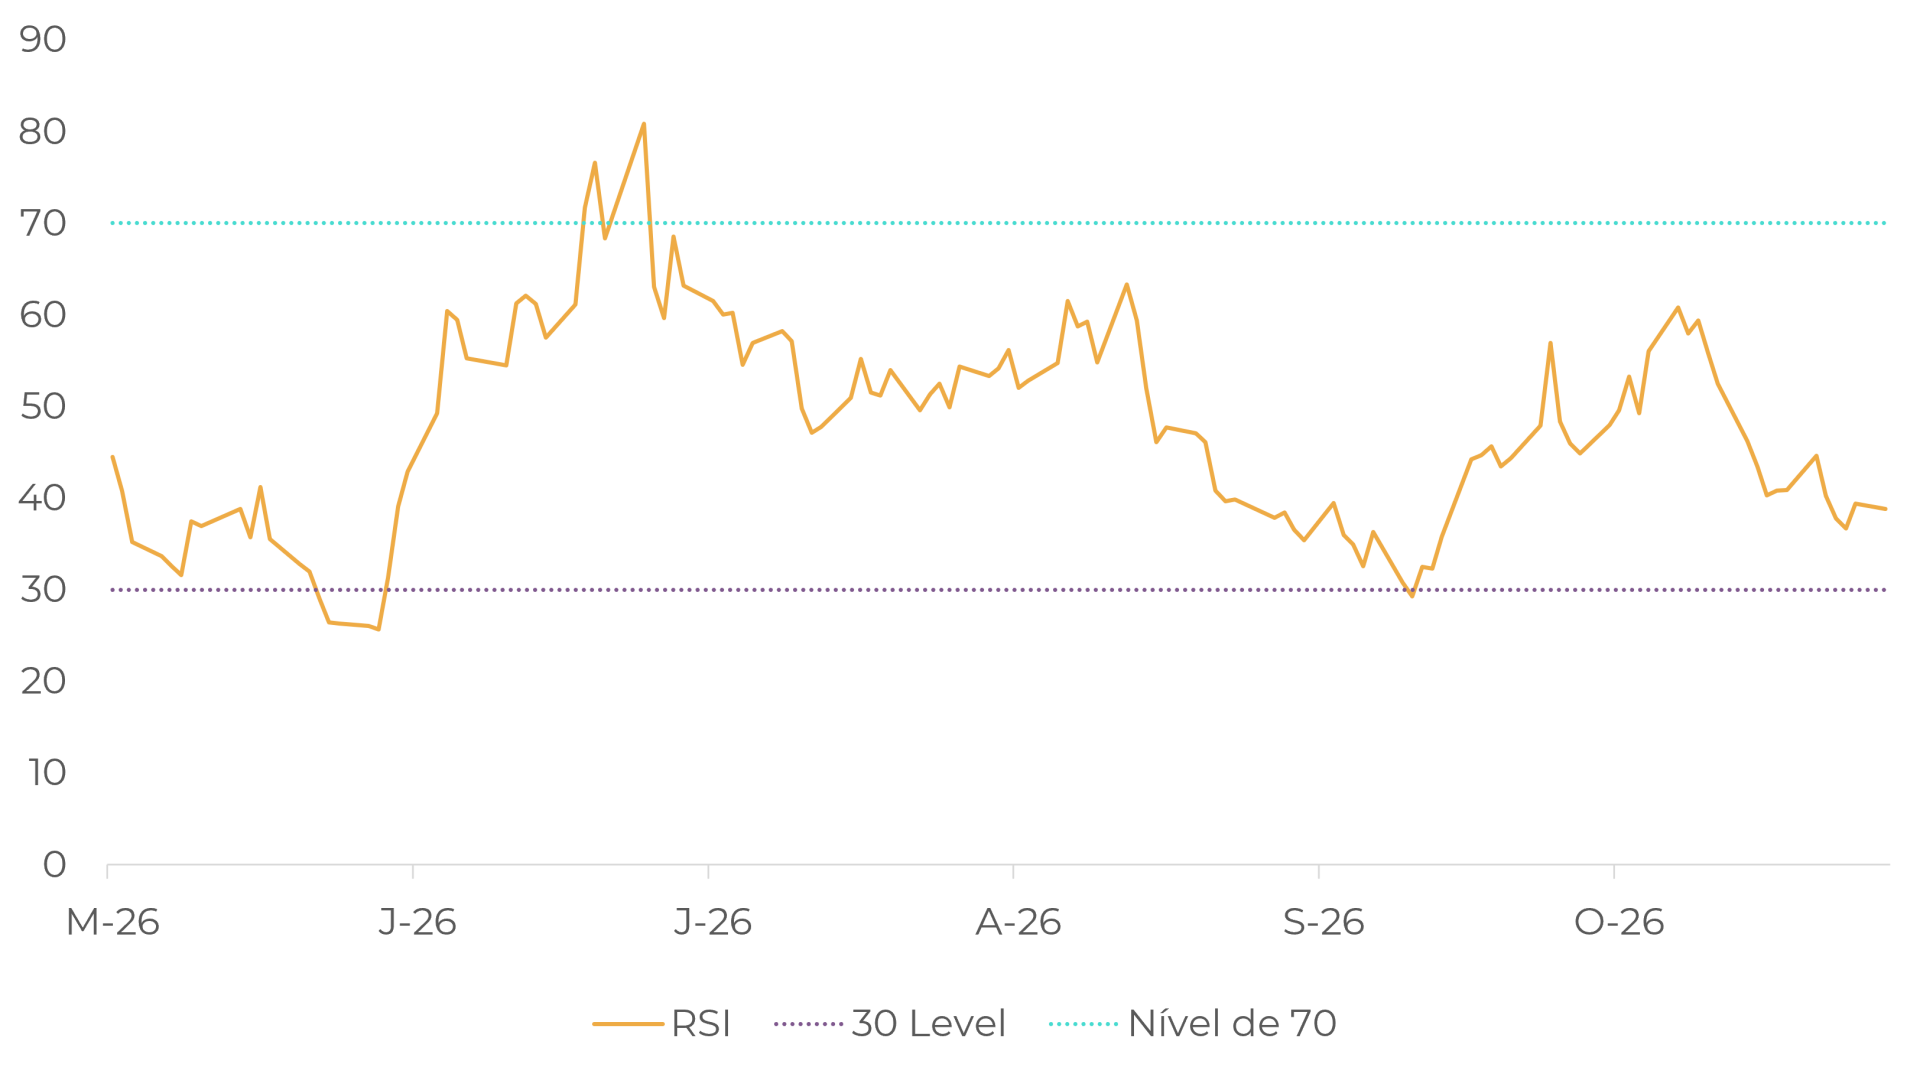
- Arabica and Robusta volatility decreased slightly in recent days, after the turmoil in prices at the end of October, reflecting mainly macroeconomic and technical factors.
- On the macro-front, current economic data from the US and an increasing risk-off sentiment triggered by the tech sector continue to support safe-haven currencies such as the dollar.
- Fundamentally, there have been no major changes. The market is waiting for the 2026/27 harvest in major origins to gain pace, while Brazilian exports are expected to increase in October.
- The size of Brazil’s 2027/28 crop remains the key price driver and will likely keep the market volatile until estimates firm up, with weather in the country being closedly monitored.
Coffee Markets Ease as Supply Pressure Mounts
Arabica: Relative Strength Index (RSI) – March/27
Source: LSEG
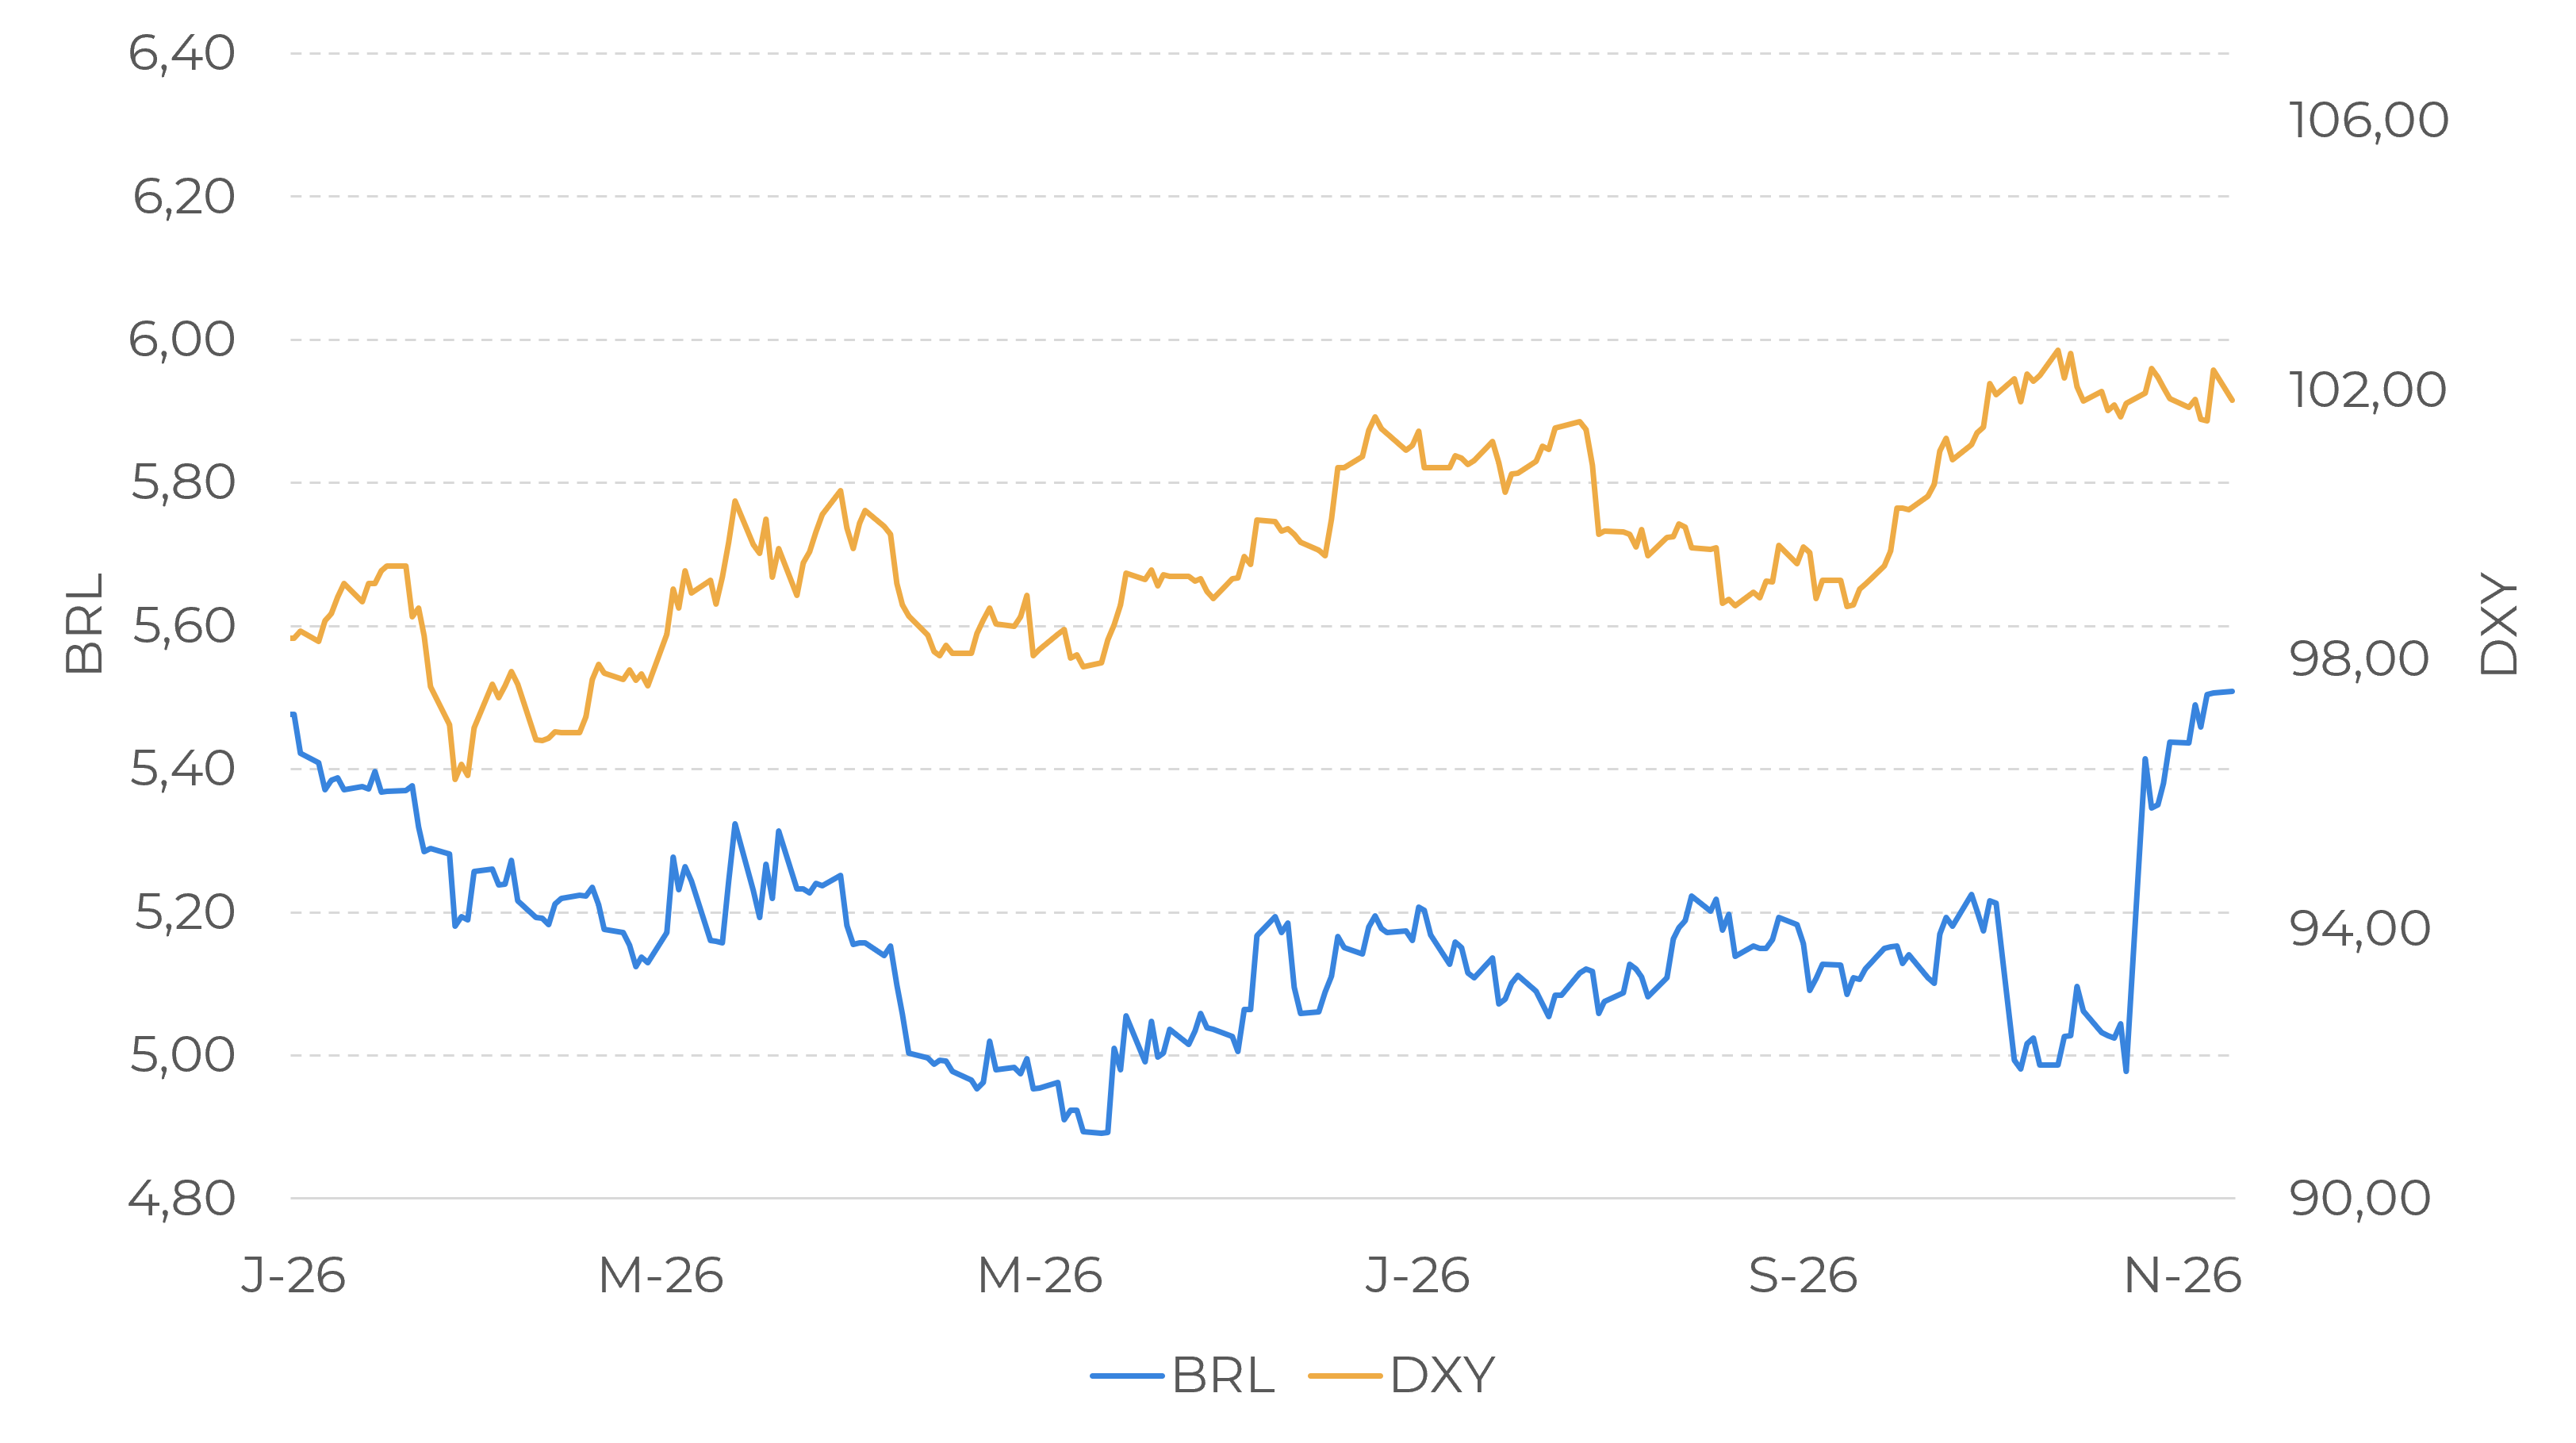
On the macro front, US October payrolls beat market expectations last week, with 165 thousand jobs added and the unemployment rate falling to 4.1%. This lifted the dollar and US Treasury yields as expectations of an interest rate hike in December increased. Investors are also reassessing global risks: a Democratic sweep of the US House and Senate sparked expectations of AI regulation, intensifying the tech selloff, while contributing to a bond market rally and increased flows into safe-haven currencies such as the dollar and the yen. In Brazil, Copom kept the Selic rate unchanged at 13.75% amid dollar strength and political uncertainty.
BRL and DXY
Source: LSEG
On the fundamental side, low stocks in consuming countries and El Niño impacts on 2026/27 and 2027/28 world production keep risks elevated. However, an expected increase in exports from Brazil and other origins, which are now in their harvest period, keeps the market trend bearish.
On the Robusta side, the Vietnamese harvest continues to gain pace and is expected to peak between the end of November and early December. Although the crop size should be similar to last season, at 30.5 M bags, exports are expected to beat the high end, following the trend of the past season. October, the first month of the 2026/27 cycle, already registered almost 2 M bags in exports, an increase of 60.2% from 2025. Differentials in the country are likely to decrease in the coming weeks (see the report here).
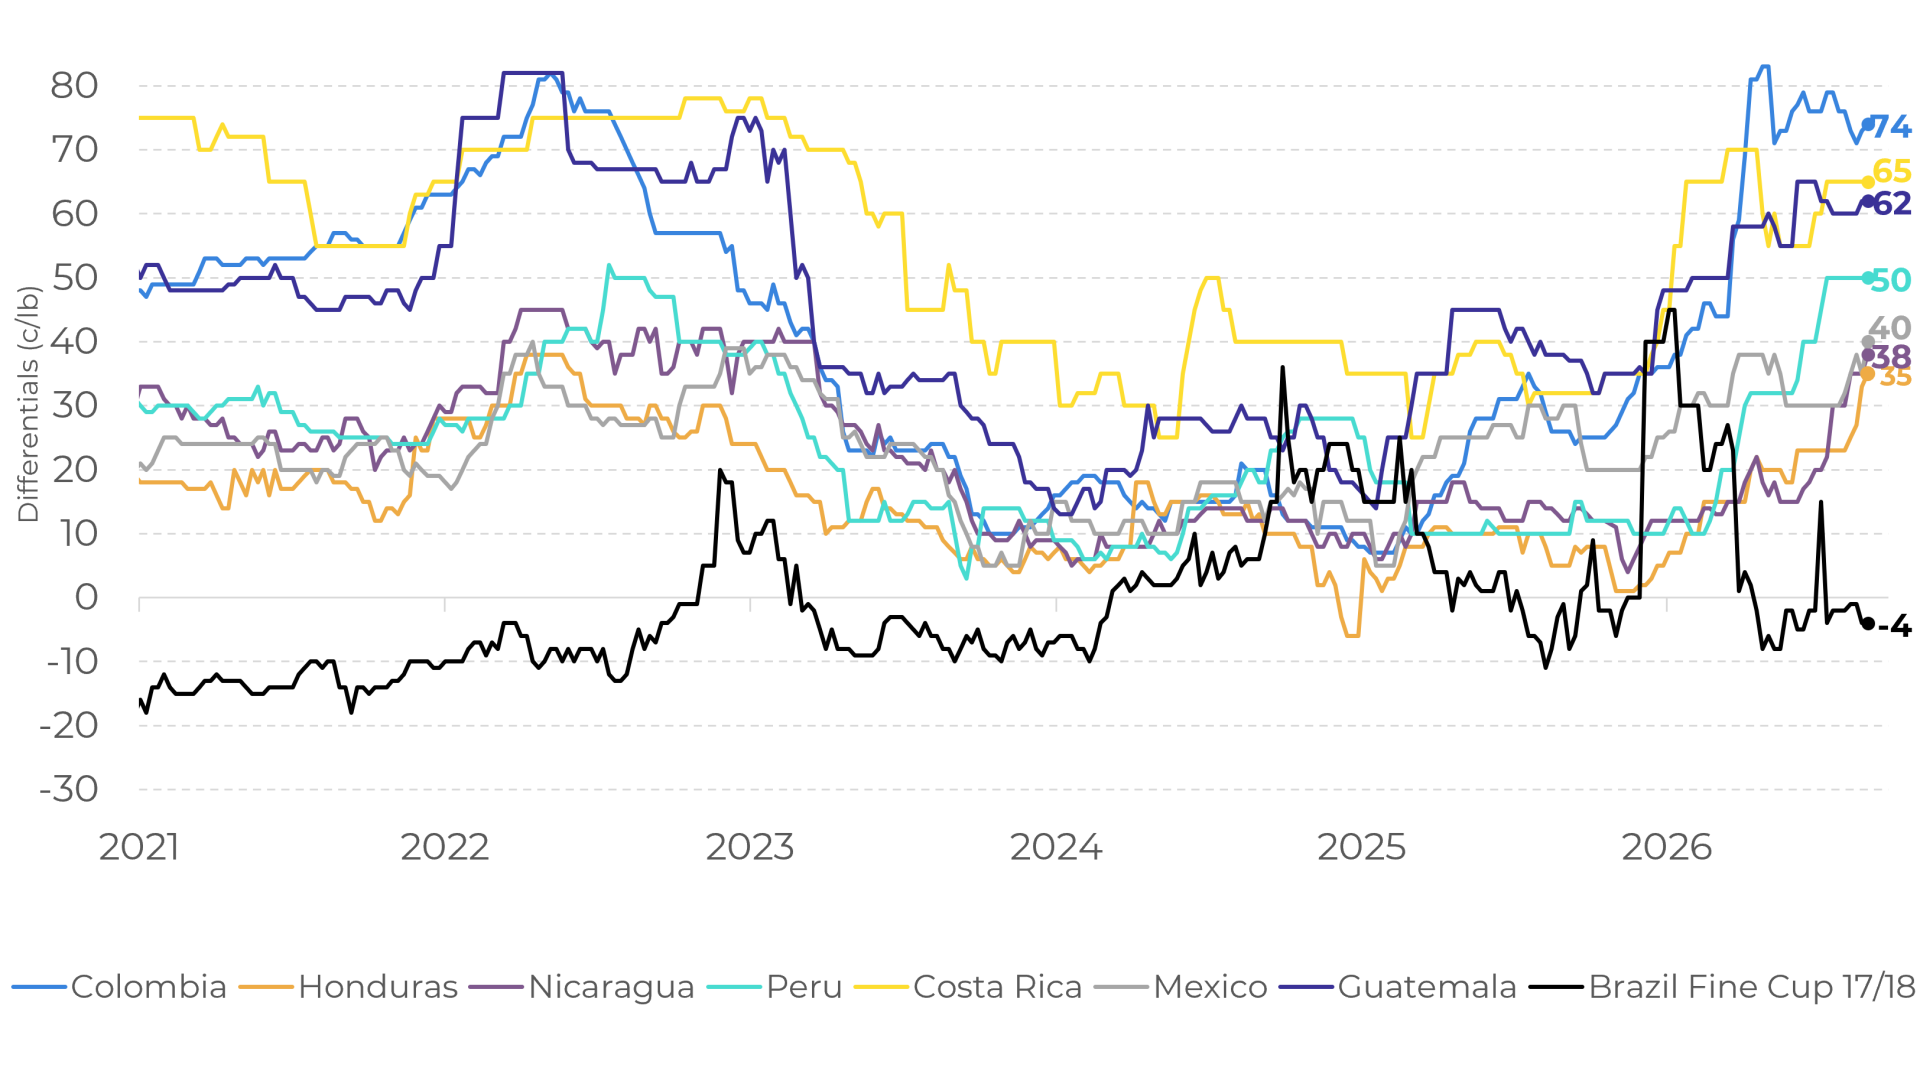
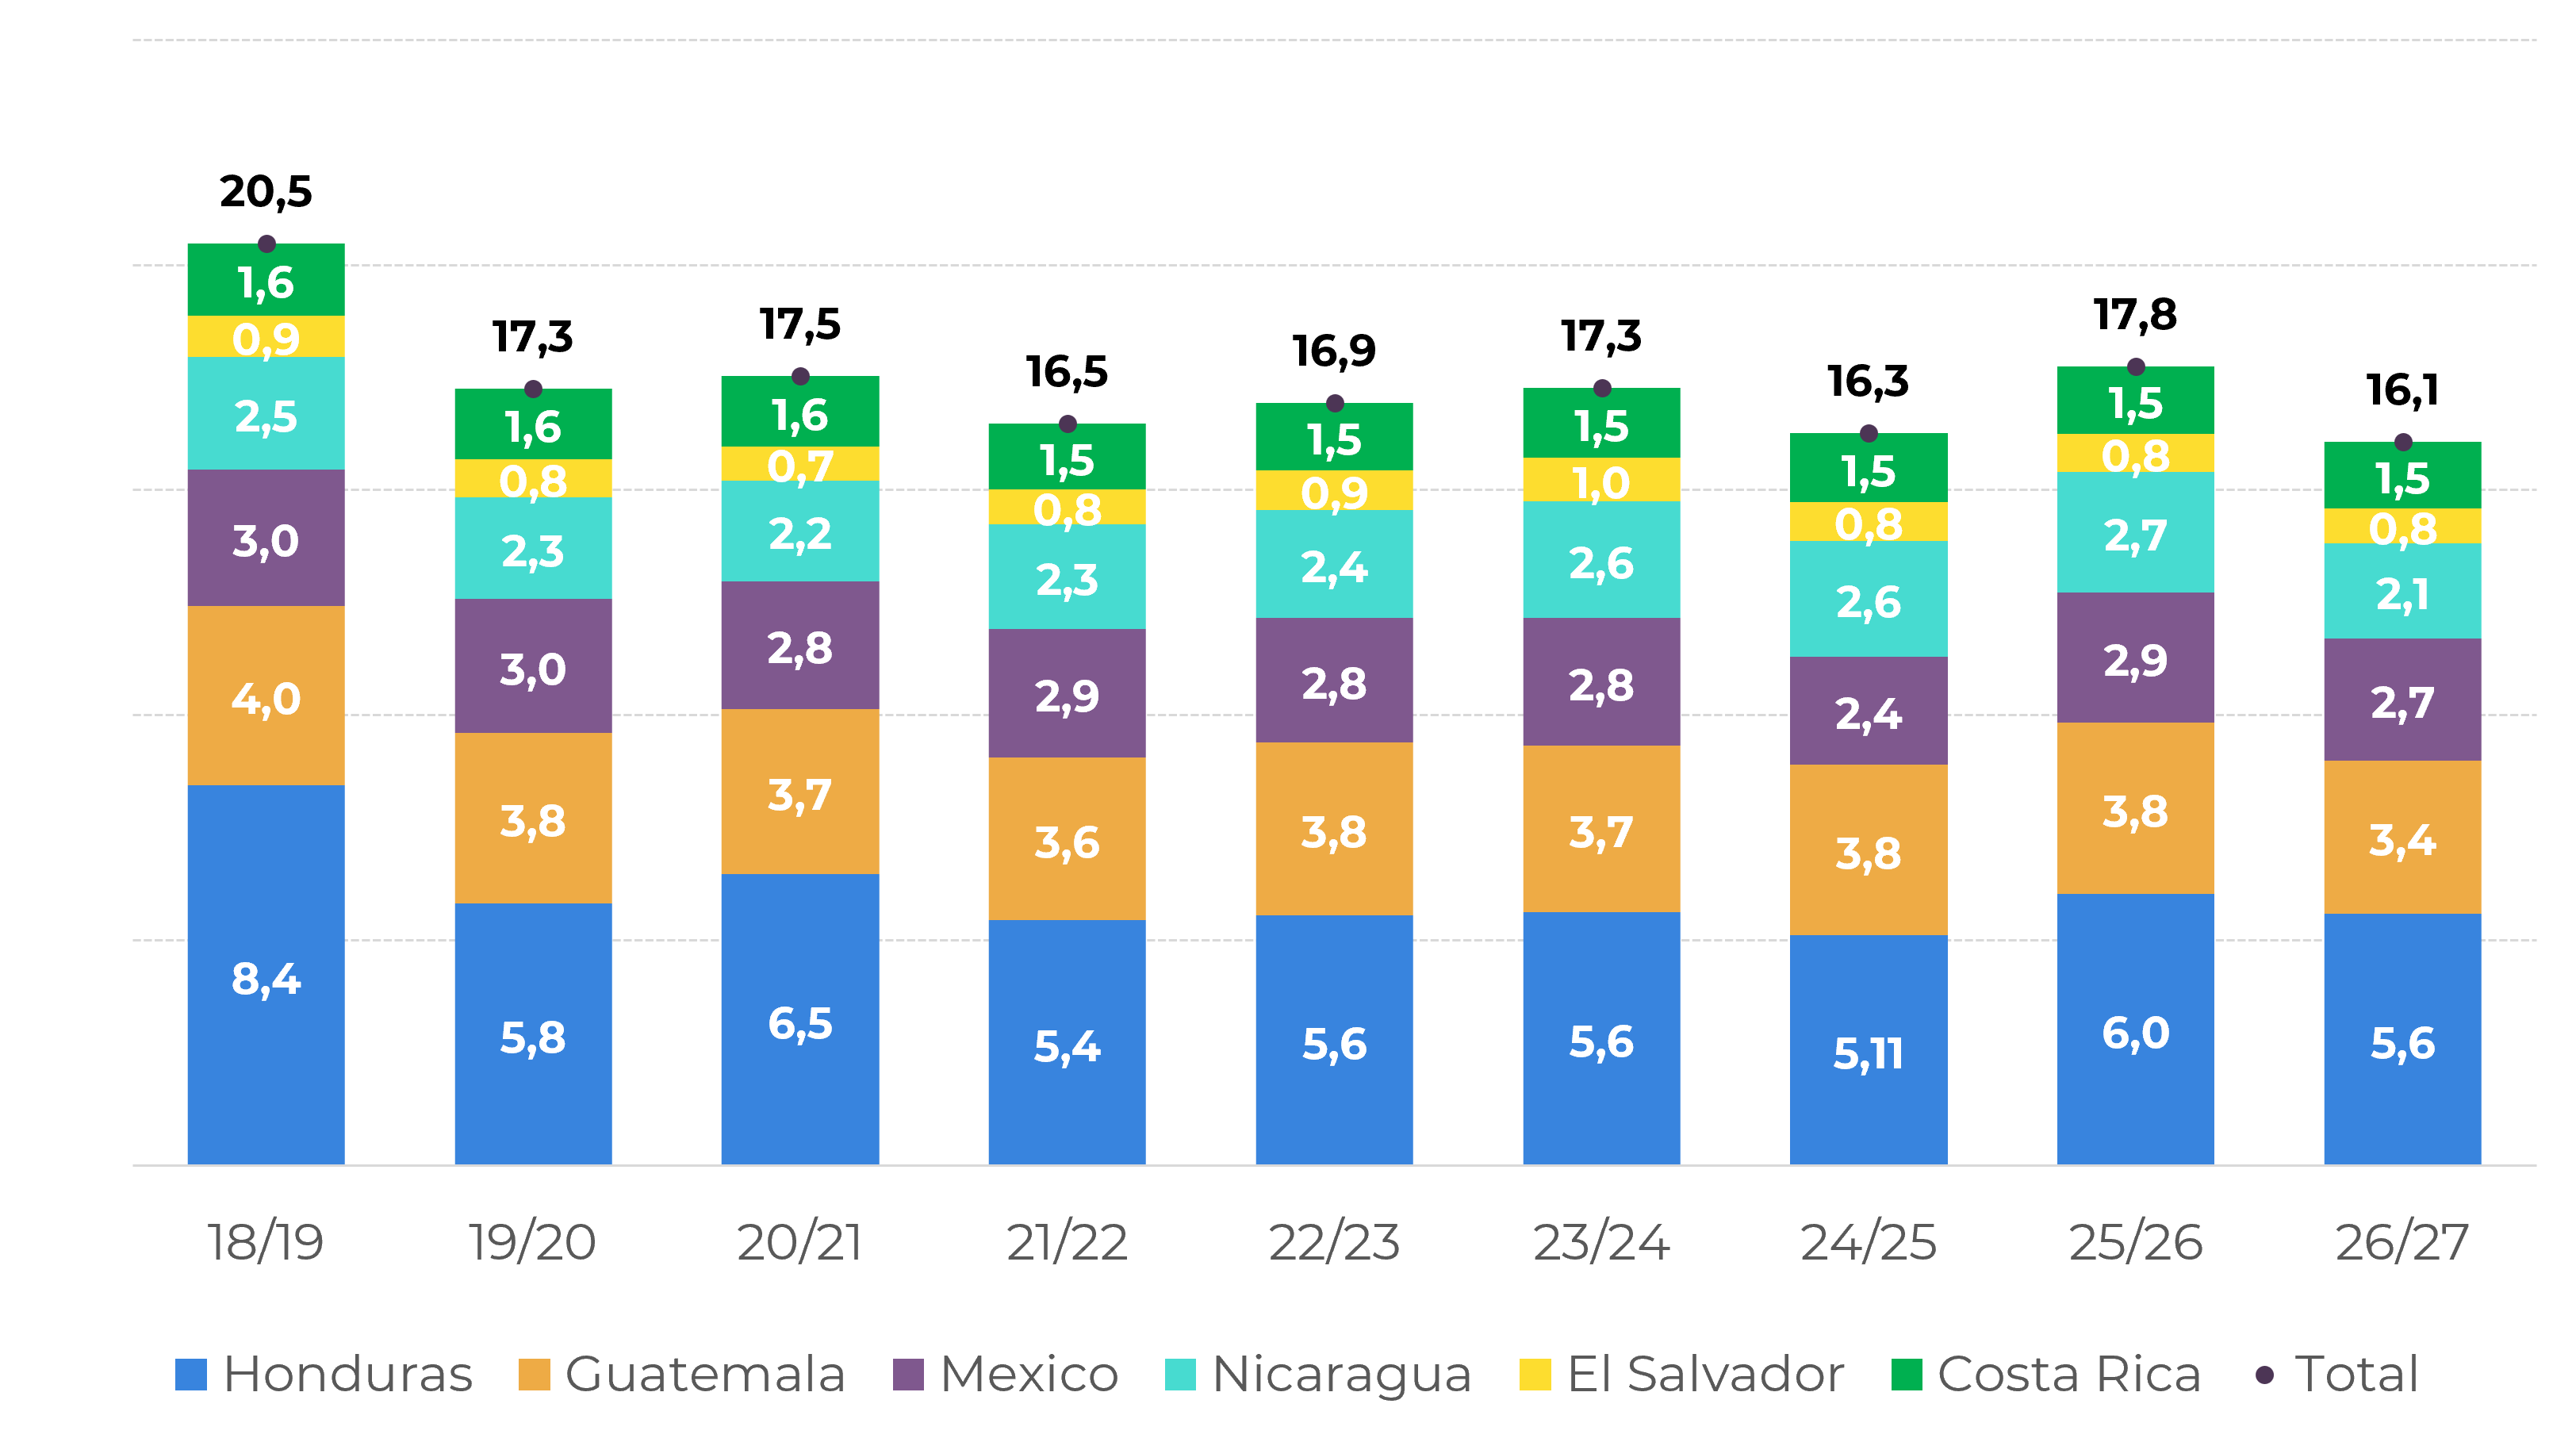
Washed Arabica differentials, on the other hand, remain at high levels. The harvest started only recently and is slowly gaining pace, while sales are also slower amid tight carry-over stocks. A higher volume of coffee is more likely to reach the market only between mid-December and early 2027. In addition, production in the 2026/27 cycle is expected to decrease by 9.9%, reflecting El Niño-related lower rainfall and higher temperatures during crop development.
Arabica Differentials (c/lb)
Source: LSEG
Despite this scenario in Central America, Brazilian exports are expected to offset the short-term supply issues, as October shipments could surpass 5 M bags, according to partial data from Cecafé through October 30. The final report is expected to be released in the coming days. This has also been reflected in the current recovery in Arabica ICE certified stocks (see report). Although still at historically low levels, stocks have shown an upward trend as more Brazilian beans arrive at ICE warehouses. Currently, more than 62 thousand bags are awaiting grading at US and European ports and, given expectations for Brazilian exports, this figure could rise in the coming week, which would likely ease market concerns.
The key factor for price direction, however, will be the size of the Brazilian 2027/28 crop. Arabica output is expected to be lower than this season given the biennial cycle, although an increase in planted area could offset part of the losses, while Conilon has potential to increase. Nevertheless, given the uneven flowering, especially in Arabica areas, concrete figures for the season are still out of the picture, as agents wait for the flowers to set and the cherries to start developing. This will likely keep the market volatile until market participants can estimate full production figures for next year.
Central America Production (M bags)
Source: Hedgepoint
In Summary
Weekly Report — Coffee
laleska.moda@hedgepointglobal.com
livea.coda@hedgepointglobal.com
Disclaimer
This document has been prepared by Hedgepoint Schweiz AG and its affiliates (“Hedgepoint”) solely for informational and instructional purposes, without intending to create obligations or commitments to third parties. It is not intended to promote or solicit an offer for the sale or purchase of any securities, commodities interests, or investment products. Hedgepoint and its associates expressly disclaim any liability for the use of the information contained herein that directly or indirectly results in any kind of damages. Information is obtained from sources which we believe to be reliable, but we do not warrant or guarantee the timeliness or accuracy of this information. The trading of commodities interests, such as futures, options, and swaps, involves substantial risk of loss and may not be suitable for all investors. You should carefully consider wither such trading is suitable for you in light of your financial condition. Past performance is not necessarily indicative of future results. Customers should rely on their own independent judgment and/or consult advisors before entering into any transactions. Hedgepoint does not provide legal, tax or accounting advice and you are responsible for seeking any such advice separately. Hedgepoint Schweiz AG is organized, incorporated, and existing under the laws of Switzerland, is filiated to ARIF, the Association Romande des Intermédiaires Financiers, which is a FINMA-authorized Self-Regulatory Organization. Hedgepoint Commodities LLC is organized, incorporated, and existing under the laws of the USA, and is authorized and regulated by the Commodity Futures Trading Commission (CFTC) and a member of the National Futures Association (NFA) to act as an Introducing Broker and Commodity Trading Advisor. HedgePoint Global Markets Limited is Regulated by the Dubai Financial Services Authority. The content is directed at Professional Clients and not Retail Clients. Hedgepoint Global Markets PTE. Ltd is organized, incorporated, and existing under the laws of Singapore, exempted from obtaining a financial services license as per the Second Schedule of the Securities and Futures (Licensing and Conduct of Business) Act, by the Monetary Authority of Singapore (MAS). Hedgepoint Global Markets DTVM Ltda. is authorized and regulated in Brazil by the Central Bank of Brazil (BCB) and the Brazilian Securities Commission (CVM). Hedgepoint Serviços Ltda. is organized, incorporated, and existing under the laws of Brazil. Hedgepoint Global Markets S.A. is organized, incorporated, and existing under the laws of Uruguay. In case of questions not resolved by the first instance of customer contact (client.services@Hedgepointglobal.com), please contact internal ombudsman channel (ombudsman@hedgepointglobal.com – global or ouvidoria@hedgepointglobal.com – Brazil only) or call 0800-8788408 (Brazil only). Integrity, ethics, and transparency are values that guide our culture. To further strengthen our practices, Hedgepoint has a whistleblower channel for employees and third-parties by e-mail ethicline@hedgepointglobal.com or forms Ethic Line – Hedgepoint Global Markets. “HedgePoint” and the “HedgePoint” logo are marks for the exclusive use of HedgePoint and/or its affiliates. Use or reproduction is prohibited, unless expressly authorized by HedgePoint. Furthermore, the use of any other marks in this document has been authorized for identification purposes only. It does not, therefore, imply any rights of HedgePoint in these marks or imply endorsement, association or seal by the owners of these marks with HedgePoint or its affiliates.