Super El Niño Raises Risks for Global Sugar Supply
- Super El Niño deepens weather risks across key sugar-producing regions.
- India and Thailand face drought stress, threatening yields and sugar recoveries.
- Brazil's rains support 27/28 cane growth but may further disrupt the current harvest.
- EU, Mexico and Indonesia add upside risk to tighter global sugar availability.
- Weather remains bullish for sugar, supporting nearby fundamentals and the March-27 contract.
Super El Niño Raises Risks for Global Sugar Supply
A very strong El Niño became the dominant weather driver for the global sugar market. Most meteorological agencies expect the phenomenon to peak between late 2026 and early 2027, creating a clear divergence between major producing regions. While Asia faces increasing drought and heat stress, Brazil has been facing wetter-than-normal conditions.
The most concerning developments are occurring in India and Thailand. India's monsoon ended significantly below average, with severe deficits concentrated in Maharashtra and Karnataka, two key sugar-producing states. Elevated temperatures have further increased crop stress during the most critical period of cane development, raising concerns over yields, sugar recovery, and crushing efficiency. This might suggest that the country might need further imports into the 26/27 season.
Standardized Precipitation Index (India | August 2026)
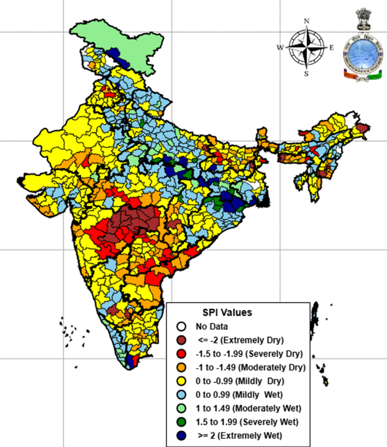
Source: India Meteorological Department
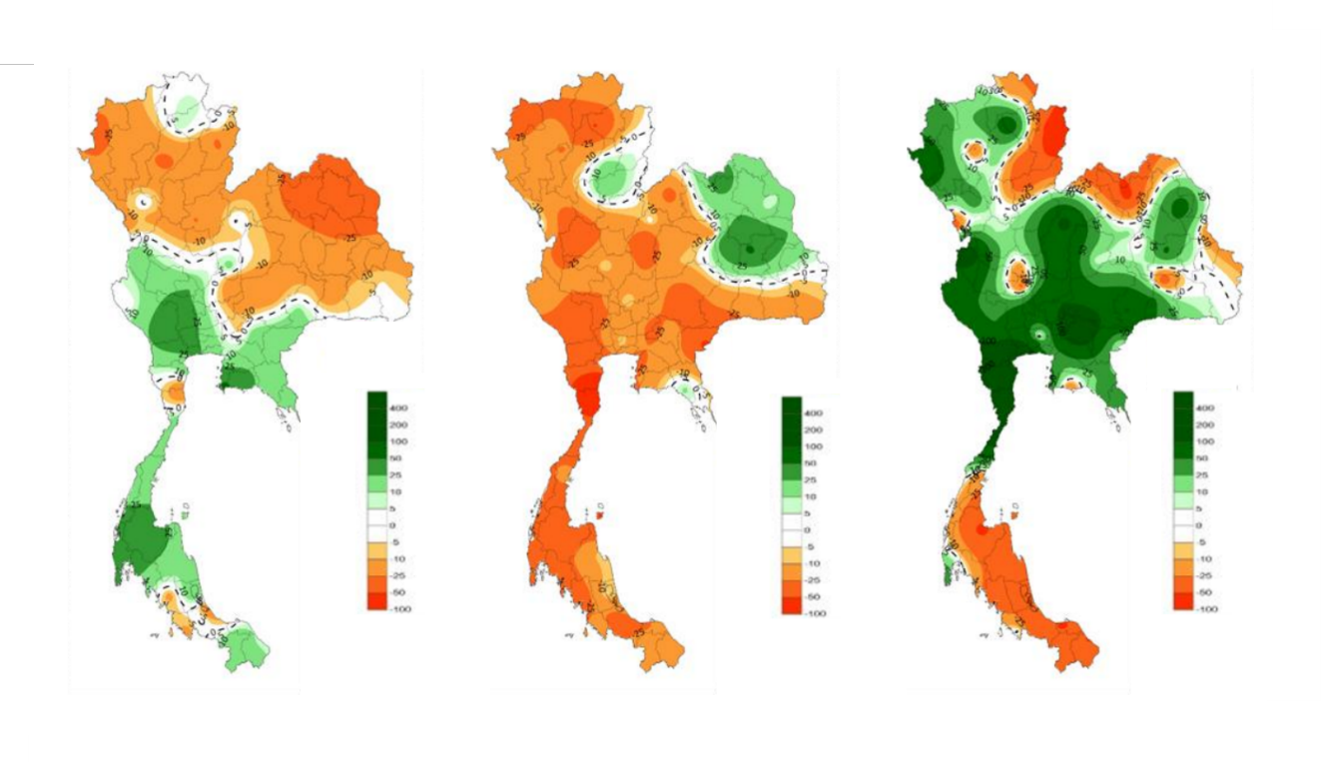
Thailand faces a similar situation, with forecasts pointing to below-normal rainfall and above-average temperatures through early 2027. Given the country's heavy dependence on rain-fed cane production, the combination of moisture deficits and heat poses a substantial threat to both yields and sugar content. November precipitation forecasts could still be positive for cane development and restrict any thought of harvesting anticipation. Therefore, the country might start only in December.
Precipitation anomaly in Thailand | September (left), October (center), and November (right) in %.
Source: Thai Meteorological Department
Indonesia's outlook is less damaging for the current crop but raises concerns for future production. The rainy season is expected to arrive later and be shorter than normal across much of the country, particularly in Java. While this should have a limited impact on cane currently being harvested, it may reduce soil moisture replenishment and constrain the development of future ratoon crops. This is especially concerning as the country might once more need to increase its demand for sugar from the international market.
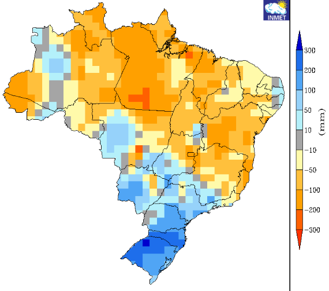
Brazil remains the main exception, in terms of precipitation pattern. Forecasts suggest above-average rainfall across most of the Center-South during the October to December period. In the short term, additional rainfall is likely to prolong harvest disruptions, lower TRS levels, and reduce operational efficiency. However, the same moisture supports root development and cane growth for the 27/28 crop, potentially improving next season's production prospects. Currently, our numbers consider some impact on TRS and cane harvest, however, there is a downside when considering current precipitation forecasts. This could add further support to the March contract, as availability during Q4/26 and Q1/27 would be tighter.
Precipitation anomaly (mm – Sep/Oct/Nov)
Source: Inmet
In the European Union, sugar beet production has already suffered from an exceptionally hot and dry summer, leading to lower yield expectations and thus, sugar availability within the group. Wetter conditions since late August provide some relief during the final stages of crop development, although excessive autumn rainfall could create harvesting difficulties. We revised our numbers down from 13.8 to 13.1Mt, -17 % down compared to 25/26 and -2.2% below the EC numbers.
Mexico presents a more balanced outlook, with wetter conditions expected in some producing regions and drier weather in others, creating both opportunities and risks depending on location. Veracruz, the leading producing state, lies within a transition zone for these patterns, heightening uncertainty regarding the potential effects of El Niño on the 2026/27 outcome. The 25/26 season ended slipping below initial expectations and, compared to previous El Niño seasons, the country tends to be highly affected. Our expectation could be considered conservative at 4.6Mt of sugar in 26/27.
From a market perspective, weather is currently acting as an ally for the bulls. The balance of risks remains skewed toward lower production and reduced recoveries across several key origins in the short-term, while the regions benefiting from improved moisture face logistical and harvest-related challenges.
Throughout the past week, speculative funds reduced their exposure to commodities as risk appetite softened following the Fed's more hawkish stance. This removed part of the short-term speculative support that had been underpinning prices, contributing to weakness in the October contract. While this bearish momentum remains consistent with the subdued demand environment discussed in previous reports, the market may begin to refocus on tightening fundamentals as the 26/27 October-September crop year gets underway, potentially bringing supply constraints more clearly into focus and supporting the March 27 contract.
Weekly Report — Sugar
Reviewed by Laleska Moda
laleska.moda@hedgepointglobal.com
Disclaimer
This document has been prepared by Hedgepoint Schweiz AG and its affiliates (“Hedgepoint”) solely for informational and instructional purposes, without intending to create obligations or commitments to third parties. It is not intended to promote or solicit an offer for the sale or purchase of any securities, commodities interests, or investment products.
Hedgepoint and its associates expressly disclaim any liability for the use of the information contained herein that directly or indirectly results in any kind of damages. Information is obtained from sources which we believe to be reliable, but we do not warrant or guarantee the timeliness or accuracy of this information.
The trading of commodities interests, such as futures, options, and swaps, involves substantial risk of loss and may not be suitable for all investors. You should carefully consider wither such trading is suitable for you in light of your financial condition. Past performance is not necessarily indicative of future results. Customers should rely on their own independent judgment and/or consult advisors before entering into any transactions.
Hedgepoint does not provide legal, tax or accounting advice and you are responsible for seeking any such advice separately.
Hedgepoint Schweiz AG is organized, incorporated, and existing under the laws of Switzerland, and a member of ARIF. ARIF (Association Romande des Intermédiaires Financiers) is a self-regulatory organization approved by the Swiss Financial Market Supervisory Authority (FINMA) for the supervision of financial intermediaries covered under Article 2, paragraph 3, of the Swiss Federal Act on Combating Money Laundering and Terrorist Financing in the Financial Sector (AMLA). Hedgepoint Commodities LLC is organized, incorporated, and existing under the laws of the USA, and is authorized and regulated by the Commodity Futures Trading Commission (CFTC) and a member of the National Futures Association (NFA) to act as an Introducing Broker and Commodity Trading Advisor. Hedgepoint Global Markets Limited is Regulated by the Dubai Financial Services Authority. The content is directed at Professional Clients and not Retail Clients. Hedgepoint Global Markets PTE. Ltd is organized, incorporated, and existing under the laws of Singapore and is classified as exempted from holding a capital markets services licence under paragraph 3A(1)(d) of the Second Schedule to the Securities and Futures (Licensing and Conduct of Business) Regulations (Rg 10). Hedgepoint Global Markets DTVM Ltda. is authorized and regulated in Brazil by the Central Bank of Brazil (BCB) and the Brazilian Securities Commission (CVM). Hedgepoint Serviços Ltda. is organized, incorporated, and existing under the laws of Brazil. Hedgepoint Global Markets S.A. is organized, incorporated, and existing under the laws of Uruguay.
In case of questions not resolved by the first instance of customer contact (client.services@Hedgepointglobal.com), please contact internal ombudsman channel (ombudsman@hedgepointglobal.com – global or ouvidoria@hedgepointglobal.com – Brazil only) or call 0800-8788408 (Brazil only).
Integrity, ethics, and transparency are values that guide our culture. To further strengthen our practices, Hedgepoint has a whistleblower channel for employees and third-parties by e-mail ethicline@hedgepointglobal.com.
“Hedgepoint” and the “Hedgepoint” logo are marks for the exclusive use of Hedgepoint and/or its affiliates. Use or reproduction is prohibited, unless expressly authorized by Hedgepoint.
Furthermore, the use of any other marks in this document has been authorized for identification purposes only. It does not, therefore, imply any rights of Hedgepoint in these marks or imply endorsement, association or seal by the owners of these marks with Hedgepoint or its affiliates.